
commercial insurance for manufacturers: 5 Powerful Benefits in 2025
Protecting Your Manufacturing Business: The Insurance Foundation
Commercial insurance for manufacturers is a specialized coverage package designed to protect manufacturing businesses against risks including equipment breakdowns, product liability, property damage, and workplace injuries. This comprehensive protection is essential for manufacturing operations of all sizes.
| Key Component | What It Covers | Why It’s Important |
|---|---|---|
| General Liability | Third-party bodily injury and property damage | Protects against common lawsuits |
| Property Insurance | Buildings, equipment, inventory | Safeguards physical assets |
| Business Income | Revenue loss during operational interruptions | Maintains financial stability |
| Product Liability | Claims related to product defects | Shields from costly product-related lawsuits |
| Workers’ Compensation | Employee injuries and illnesses | Required by law in most states |
The manufacturing industry contributes over $2.35 trillion to the U.S. economy annually and employs more than 12 million workers. With nearly 38,000 fires reported each year at industrial facilities and equipment failures causing almost half of all unplanned downtime, manufacturers face unique risks that require custom insurance solutions.
As the owner of Copeland Insurance Agency with specialized certifications in commercial insurance for manufacturers, I’ve guided countless manufacturing businesses through the complex landscape of risk management and coverage selection. My experience has shown that the right insurance partnership is as crucial to operational success as reliable equipment and skilled workers.
The Manufacturing Backbone
The manufacturing sector represents 10.9% of the U.S. GDP, making it a cornerstone of our economy. From small local fabricators to large multinational corporations, manufacturers create the products that drive our daily lives and global commerce. This vital economic engine requires protection that’s as specialized and robust as the operations themselves.
At Copeland Insurance Agency, we understand that each manufacturing business—whether in Kansas, Arizona, or any of the other states we serve—faces a unique set of challenges and exposures that demand customized insurance solutions.

Manufacturing Risk Landscape & Legal Requirements
When you’re running a manufacturing business, you’re navigating through a minefield of potential risks every day. From equipment failures to workplace accidents, these challenges can threaten not just your bottom line, but sometimes the very survival of your business.
Consider this sobering fact: FEMA reports that approximately 25% of businesses never reopen their doors after experiencing a major disaster. For manufacturers with substantial investments in specialized equipment and facilities, this statistic isn’t just concerning—it’s a call to action for proper protection.
Main Risks & Exposures
The manufacturing world faces unique challenges that other industries simply don’t encounter. Equipment breakdown is perhaps the most immediate threat, causing nearly half of all unplanned downtime. When your production line grinds to a halt, so does your revenue stream.
Industrial fires pose another significant danger, with over 37,900 reported annually at manufacturing properties. These aren’t just minor incidents—they can devastate buildings, destroy inventory, and shut down operations for months.
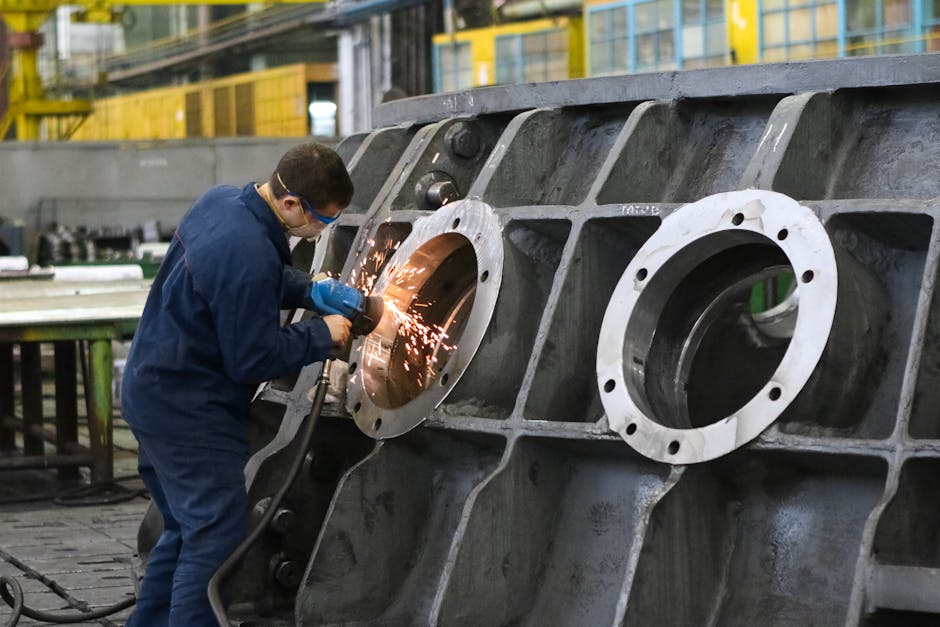
The human element remains vulnerable too. Manufacturing accounts for about 15% of all nonfatal workplace injuries and illnesses according to the Bureau of Labor Statistics. From minor cuts to life-altering accidents with heavy machinery, employee injuries represent both a human and financial cost.
In today’s interconnected world, supply chain disruptions can be just as damaging as physical disasters. When raw materials don’t arrive or shipping logistics fail, production schedules collapse, potentially triggering contract penalties and customer dissatisfaction.
One of our clients in Junction City, Kansas learned this lesson firsthand: “We had to shut down our manufacturing facility for a few days after a huge tree limb fell across one of the power lines. Without business interruption coverage, we would have lost tens of thousands in revenue during the downtime.”
The digital revolution brings its own risks too. As manufacturing becomes more automated, cyber threats have evolved from a minor concern to a major vulnerability. A single breach can compromise sensitive data, halt production, or even damage physical equipment through compromised control systems.
Mandatory Coverages & Regulations
Some insurance coverages aren’t just good business practice—they’re legally required. Workers’ compensation insurance tops this list, mandatory in all states where you employ people. This coverage handles medical expenses and lost wages when workplace injuries occur, though specific requirements vary across Kansas, Arizona, and other states where Copeland Insurance Agency operates.
If your manufacturing business owns vehicles, commercial auto liability insurance is another legal requirement in most states, providing essential coverage for bodily injury and property damage.
Depending on your manufacturing processes, environmental liability coverage may also be mandated by federal and state regulations, especially if your operations involve potentially hazardous materials or waste.
OSHA regulations add another layer of complexity, imposing specific safety requirements that directly impact both your risk profile and insurance costs. Staying compliant isn’t just about avoiding fines—it’s about creating a safer workplace and maintaining more affordable insurance premiums.
At Copeland Insurance Agency, we help manufacturers understand both their required coverages and the optional protections that might mean the difference between recovery and closure after an unexpected event. The latest injury statistics for manufacturing workers continue to emphasize why proper coverage isn’t just a business decision—it’s an essential investment in your company’s future.
Building Your Commercial Insurance for Manufacturers Portfolio
Creating a comprehensive insurance program for your manufacturing operation isn’t just about checking boxes—it’s about building a safety net that perfectly fits your unique business needs.
“Commercial Insurance for Manufacturers” Essentials
General Liability Insurance serves as the bedrock of any solid manufacturing insurance program. This fundamental coverage steps in when someone claims your business caused them bodily injury, damaged their property, or harmed them through your advertising.
Picture this: A potential client tours your facility, slips on a recently mopped floor, and breaks their wrist. Your General Liability Insurance would cover their medical bills and your legal defense if they decide to sue. It also protects you when your delivery person accidentally damages a customer’s loading dock or if a competitor claims you copied their slogan in your latest ad campaign.
For manufacturers, this coverage typically includes product liability protection—an absolute must-have that shields you when someone claims your product caused harm or damage.
As one of our Salina, KS clients put it: “When a customer claimed our product caused an injury, our general liability coverage saved us. The legal costs alone would have sunk our small manufacturing shop without it.”
Core Property Protections
Your physical assets represent massive investments that Commercial Insurance for Manufacturers must safeguard. Commercial Property Insurance protects everything from your production facility to the smallest bolt in your inventory:
Your manufacturing buildings and facilities, specialized production machinery, raw materials sitting in storage, half-finished products on the line, and completed inventory ready for shipping all need protection. Even your office equipment, furniture, outdoor signage, and security fencing fall under this essential coverage.
At Copeland Insurance Agency, we tailor your property coverage to address manufacturing-specific concerns. We can structure your policy with replacement cost valuation for that custom-built equipment that would be impossible to find “used.” We can accommodate seasonal inventory fluctuations and include manufacturers’ selling price coverage—which means if disaster strikes your finished goods, you’re compensated at their selling price, not just what you spent making them.
Standard policies often contain surprises in the form of limitations or exclusions for risks like floods or equipment breakdown. We’ll help identify these potential gaps before they become costly problems.
Income & Liability Safety Nets
When disaster forces your production line to halt, the financial impact goes far beyond damaged equipment. Two crucial coverages address these broader financial threats:
Business Interruption Insurance becomes your financial lifeline when covered property damage forces you to slow or stop operations. Our Business Interruption Insurance Coverage replaces lost profits, covers ongoing expenses like rent and loan payments, funds temporary relocation if needed, and helps you keep paying valuable employees so they don’t find jobs elsewhere during your downtime.
Product Liability Insurance provides specialized protection against claims that your product caused harm. While often included in general liability policies, manufacturers with higher-risk products may need improved coverage through our dedicated Product Liability Insurance. This covers legal defense costs, settlements or judgments, medical costs for injured parties, and with the right endorsements, even product recall expenses.
“The fire that damaged our main production line could have been the end of us,” shared a manufacturing client from Manhattan, KS. “But our business interruption insurance kept us afloat during six weeks of repairs. We kept our best employees and didn’t lose a single major customer—that coverage literally saved our business.”
| Coverage Type | Standard Policy | Business Owner’s Policy (BOP) |
|---|---|---|
| General Liability | Purchased separately | Included |
| Property Insurance | Purchased separately | Included |
| Business Interruption | Optional add-on | Often included |
| Equipment Breakdown | Optional add-on | Often included |
| Professional Liability | Purchased separately | Not typically included |
| Workers’ Compensation | Purchased separately | Not included |
| Commercial Auto | Purchased separately | Not included |
For many small to mid-sized manufacturers, a Business Owner’s Policy (BOP) offers smart savings by bundling general liability, property, and business interruption coverage together at a lower cost than purchasing these crucial protections separately. At Copeland Insurance Agency, we’ll help you determine whether individual policies or a BOP makes more sense for your specific manufacturing operation.
Specialized Coverages & Supply Chain Resilience
Beyond the basics, your manufacturing operation likely needs specialized protection that addresses the unique challenges of your industry. Let’s explore how the right insurance can strengthen your business against unexpected disruptions.
Equipment & Technology Safeguards
Modern manufacturing relies heavily on specialized equipment and technology. When these systems fail, production grinds to a halt—and that’s when the right coverage becomes invaluable.
Equipment Breakdown Insurance goes beyond what standard property insurance covers. While property insurance protects against external threats like fires or storms, equipment breakdown steps in when machinery fails due to mechanical or electrical issues. This coverage helps with repair costs, replacement expenses, and even the business income you lose while waiting for equipment to be fixed.
One of our clients in Topeka put it perfectly: “When our CNC machines were compromised by malware, our cyber policy covered not just the IT recovery costs but also the production downtime while systems were restored.” As manufacturing becomes more automated and connected, this protection becomes increasingly essential.
Cyber Liability Insurance has transformed from an optional add-on to a necessity for modern manufacturers. With smart factories, IoT sensors, and digital supply chains, cyber vulnerabilities can impact your physical operations in ways that weren’t possible a decade ago. This coverage protects you against data breaches, ransomware attacks, and the business interruption that follows a cyber incident.
“Commercial Insurance for Manufacturers” & Product Recalls
Nothing strikes fear into a manufacturer’s heart quite like a product recall. The financial impact goes far beyond just replacing products—it can damage your reputation, trigger lawsuits, and create a PR nightmare.
Product Recall Insurance provides critical protection when you find a product defect. It covers the costs of notifying customers, shipping and disposing of recalled items, and replacing defective products. More importantly, it can help fund the crisis management and public relations efforts needed to protect your brand.
A manufacturing client from Wamego shared their experience: “We had to issue a recall when we realized one of our products caused injuries. Our commercial insurance for manufacturers coverage not only handled the logistical expenses but also funded the PR campaign that helped us maintain customer trust.”
Protecting Against Supply-Chain Disruptions
If the pandemic taught manufacturers anything, it’s that supply chains are fragile. When suppliers can’t deliver or transportation networks break down, your production suffers—even when nothing has happened to your facility.
Contingent Business Interruption Insurance steps in when your suppliers or customers experience disruptions that impact your operations. Unlike standard business interruption coverage, which responds to damage at your location, this protection addresses income losses from problems elsewhere in your supply chain.
Ocean Marine and Inland Marine Insurance protect your materials and products while they’re in transit. Our Inland Marine Insurance is particularly valuable if you regularly ship finished goods or receive raw materials across the country.
For manufacturers with their own delivery fleet, Fleet Insurance provides comprehensive protection for both vehicles and liability exposures.
Trade Credit Insurance offers peace of mind when shipping products to customers on credit terms. If a customer can’t pay due to bankruptcy or other financial issues, this coverage ensures you don’t bear the full financial burden.
At Copeland Insurance Agency, we believe that true supply chain resilience combines smart insurance coverage with strategic business planning. We’ll help you identify the right mix of coverages to protect against disruptions while also discussing practical steps like identifying backup suppliers, maintaining safety stock of critical materials, and developing solid contingency plans.
In today’s interconnected manufacturing world, your biggest risk might not be a fire in your facility—it could be a flood at your supplier’s warehouse or a cyber attack on your logistics provider. The right commercial insurance for manufacturers package anticipates these complex dependencies and provides protection accordingly.
Balancing Cost, Claims & Continuous Risk Management
Finding the sweet spot between comprehensive protection and affordable premiums is something we help manufacturers achieve every day at Copeland Insurance Agency. It’s not just about buying insurance—it’s about creating a holistic risk management strategy that works for your specific operation.
Determining Adequate Limits & Umbrella Needs
When we sit down with manufacturing clients, one of the most important conversations involves setting appropriate coverage limits. This isn’t a one-size-fits-all decision—it requires thoughtful analysis of your unique situation:
“We initially thought our $1 million general liability policy was adequate until our insurance advisor showed us the average product liability settlement in our industry,” shared a manufacturing client from Riley, KS. “Adding a $5 million umbrella policy costs less than we expected and helps us sleep better at night.”
Your coverage limits should reflect the true scope of your risk exposure. For many manufacturers, standard policy limits simply don’t provide enough protection against worst-case scenarios. That’s where Commercial Umbrella Insurance becomes invaluable—providing that extra layer of protection when primary policies reach their limits.
We consider several key factors when helping you determine appropriate coverage:
Your physical assets – The full replacement value of specialized equipment and facilities can be surprising when you add it all up.
Product liability exposure – Some products naturally carry higher liability risks than others.
Contractual requirements – Many clients and vendors may require specific coverage limits in your agreements.
Financial resilience – Your company’s ability to absorb certain losses helps determine where insurance needs to step in.
The premium you’ll pay for your commercial insurance for manufacturers package depends on numerous variables—from the obvious ones like business size and types of products you make, to less apparent factors like your safety programs and employee training protocols. Your claims history, location, and even the specific materials you work with all influence your rates.
Filing a Claim & Moving Forward
Even with the best preventive measures, claims happen. When they do, knowing how to steer the process makes all the difference.
A manufacturer in Abilene, KS told us: “After a fire damaged our warehouse, our Copeland agent walked us through every step of the claims process. They even helped us find temporary space to continue limited operations while repairs were underway.”
When you experience a loss, time is often of the essence. Report incidents promptly to your agent or carrier, and document everything thoroughly with photos, videos, and witness statements when applicable. Take reasonable steps to prevent additional damage, but don’t make permanent repairs until an adjuster has assessed the situation.
Throughout the claims process, communication is key. Stay in regular contact with your agent and the claims adjuster, providing requested information promptly. Keep detailed records of all expenses related to the incident—from emergency repairs to temporary relocation costs.
At Copeland Insurance Agency, our involvement doesn’t end when your claim is settled. We work with you to analyze what happened and identify preventive measures that might help avoid similar incidents in the future. Our Risk Management services help you turn claims experiences into opportunities for improvement.

The most successful manufacturers we work with view insurance as just one component of a comprehensive risk management strategy. They implement safety programs, maintain equipment religiously, train employees thoroughly, and work proactively with us to identify emerging risks before they become problems. This approach not only helps prevent losses but often leads to more favorable premium rates over time.
Frequently Asked Questions about Commercial Insurance for Manufacturers
What businesses need manufacturing insurance?
When we talk about commercial insurance for manufacturers, we’re not just referring to massive factories with assembly lines. The truth is, if you’re making products—whether in a sprawling facility or a converted garage—you need specialized coverage.
The manufacturing world is wonderfully diverse. We’ve helped protect food processors crafting artisanal sauces, metal fabricators creating custom parts, electronics manufacturers assembling circuit boards, and furniture makers building heirloom-quality pieces. Other businesses that benefit from manufacturing insurance include textile producers, plastics manufacturers, chemical companies, automotive parts makers, medical device manufacturers, and printing operations.
One of our clients in Manhattan, KS started making custom metal signs in his home workshop. He was shocked to find his homeowner’s policy specifically excluded his manufacturing activities. “I thought I was covered until my agent at Copeland explained the gaps,” he told us. “Getting proper commercial insurance for manufacturers gave me peace of mind I didn’t even know I was missing.”
How does insurance handle product recall costs?
Product recalls can feel like a nightmare scenario for manufacturers. Without proper coverage, they can drain your finances and damage your reputation.
A comprehensive product recall policy creates a financial safety net for the entire recall process. It covers notification expenses to alert distributors, retailers, and consumers about the problem. It handles the logistics costs of retrieving, storing, and properly disposing of recalled products. The policy also addresses replacement costs to repair or substitute defective items.
Beyond these direct expenses, good recall coverage helps with the hidden costs: lost profits during the disruption, professional crisis management to protect your brand’s reputation, and even expenses incurred by your distributors or retailers because of your recall.
“When we finded a potential safety issue with one of our food products,” shared a client from Junction City, “our product recall coverage made all the difference. It not only covered the direct costs but also funded the communications strategy that helped preserve customer trust.”
It’s worth noting that standard general liability policies typically provide limited or no coverage for recall expenses. This is why specialized protection is so vital for manufacturers of all sizes.
How can manufacturers reduce premiums?
Insurance is an investment in your business’s future, but we understand you need to manage costs. The good news is you can take practical steps to lower your premiums while maintaining solid protection.
Building a culture of safety pays dividends. Well-documented safety procedures, regular employee training, and consistent enforcement of protocols can substantially reduce workers’ compensation premiums. One of our manufacturing clients in Marysville, KS implemented our recommended safety program and watched their workers’ comp premium decrease by 22% over just two years—even while adding employees and expanding operations.
Bundling multiple policies with one carrier often results in discounts between 5-15%. Similarly, choosing appropriate deductibles can lower your premium costs, though it’s important to select amounts your business can comfortably handle if a claim occurs.
Smart investments in your facility can also reduce costs. Fire suppression systems, security measures, and regular equipment maintenance not only protect your business but can qualify you for premium discounts with many carriers.
Don’t overlook the importance of accurate property valuations. Regularly updating your property schedules ensures you’re not paying for unnecessary coverage while still maintaining adequate protection for your assets.
Finally, working with an independent agency like Copeland Insurance gives you access to multiple carriers, allowing us to shop your coverage and find the best combination of protection and value for your specific manufacturing operation. We’re not tied to a single company’s products, so we can truly focus on finding the right fit for your needs.
Conclusion
Commercial insurance for manufacturers isn’t just another business expense—it’s a vital investment in your company’s future. In the manufacturing world, where a single unexpected event can threaten everything you’ve built, the right insurance coverage provides both protection and peace of mind.
At Copeland Insurance Agency, we’ve dedicated ourselves to becoming true manufacturing insurance specialists across Kansas, Arizona, and all the states we serve. We’ve seen how each manufacturing operation faces its own unique challenges—from the small custom fabricator to the large-scale production facility.
What sets us apart isn’t just our insurance expertise, but our genuine commitment to your business success. One of our clients in Junction City put it best: “Copeland doesn’t just sell us policies—they help us understand our risks and build protection that grows with our business.”
We believe in building relationships that last. When you work with us, you’re not just getting an insurance policy—you’re gaining a partner who understands the manufacturing landscape and cares about your bottom line. We’ll be there when equipment breaks down, when supply chains falter, or when the unexpected threatens your operations.
Our approach combines thorough risk assessment, customized coverage solutions, and ongoing support as your manufacturing business evolves. We take the time to walk your production floor, understand your processes, and identify both obvious and hidden risks before they become problems.
Whether you’re running a family-owned machine shop in Salina or managing a growing food processing operation in Topeka, we provide the guidance and protection your business deserves. Our manufacturing clients consistently tell us that having Copeland in their corner gives them the confidence to focus on what they do best—creating quality products.
Ready to strengthen your manufacturing operation’s safety net? Visit our Commercial Property Insurance page or reach out directly for a personalized consultation. Your manufacturing business is too important to protect with anything less than expert coverage designed specifically for your needs.