
Small business bond insurance—more accurately known as a surety bond—is a three-party guarantee that protects your clients from financial loss if you fail to deliver on your contract. It's not insurance for your business; it's a promise, backed by a third party, that you'll get the job done right.
What Is a Surety Bond and Why Does It Matter
Many business owners in Kansas and Missouri see the phrase "bonded and insured" everywhere but don't quite grasp what being bonded really means. While insurance protects your business from its own accidents and liabilities, a surety bond is all about protecting your client. Think of it as a powerful stamp of approval that signals your reliability and financial stability.
Imagine you're a homeowner about to hire a contractor for a major kitchen remodel. You need to know they’ll finish the job and pay their suppliers. A surety bond gives you that confidence. It acts like a co-signer on a loan, telling the world that a reputable surety company has thoroughly vetted your business and is willing to guarantee your performance.
A surety bond is fundamentally a credit instrument. It's an agreement where one party, the surety, guarantees the performance of a second party, the principal, to a third party, the obligee.
The Three Key Players in a Surety Bond Agreement
Understanding the role each person plays is the first step to seeing how these guarantees work. Every surety bond boils down to a simple but critical relationship between three parties. Here's a quick reference to understand who's who.
| Term | Who They Are | Their Role in the Agreement |
|---|---|---|
| The Principal | This is your small business. | You are the one performing the work and are required to fulfill the contract terms. |
| The Obligee | This is your client or the entity requiring the bond (e.g., a government agency). | They are the party protected by the bond, receiving the guarantee. |
| The Surety | This is the bonding or insurance company that issues the bond. | They guarantee to the obligee that you (the principal) will meet your obligations. |
So, if the principal (your business) fails to perform as promised, the obligee (your client) can file a claim against the bond. The surety company then steps in to make sure the obligation is met. However, it's crucial to remember that you, the principal, are ultimately responsible for reimbursing the surety for any claims they pay out.
You can dive deeper into the different kinds of commercial bonds available to see which one fits your specific industry.
Why This Guarantee Is a Growth Tool
For small businesses, especially in competitive fields like construction, getting a surety bond is more than just checking a box—it’s a strategic move. It opens doors, allowing you to bid on larger public works projects in places like Kansas City or Wichita, which almost always require bonds.
This guarantee builds incredible credibility and lets you compete on a level playing field with bigger, more established companies. While surety bonds aren't loans, they often involve a fee, and certain government programs can make them more accessible. For example, understanding the details of an SBA guarantee fee can offer insight into related costs.
Ultimately, a bond is an essential tool for unlocking new opportunities and proving your business is built on a solid foundation of trust.
The Common Types of Bonds Your Business May Need
Just like a good mechanic has a whole toolbox for different engine problems, small business bond insurance isn't a single product. It’s a category of guarantees that come in different forms, each designed to solve a specific business need.
The first step is figuring out which tool is right for the job. Bonds generally fall into two big buckets: Contract Bonds and Commercial Bonds. Each one serves a totally different purpose, and for business owners in Kansas and Missouri, knowing the difference is key to winning work and operating legally.
The World of Contract Bonds
Contract bonds are the absolute backbone of the construction world. Think of them as a project-specific safety net for your client. They guarantee that a project gets done according to the plans and promises you made.
If you’re bidding on public works projects, you’ll almost always be required to have them. They're also becoming more and more common in the private sector. These bonds work together throughout a project’s life:
- Bid Bonds: You submit this bond with your project bid. It's your financial promise that if you win the job, you’ll actually sign the contract and secure the other necessary bonds. It shows you’re a serious contender.
- Performance Bonds: Once you’ve won the contract, this bond guarantees you'll complete the project as specified. If a contractor in Wichita defaults on building a new city park, this bond protects the city's investment and ensures the project gets finished.
- Payment Bonds: This one works hand-in-hand with a performance bond. It guarantees you’ll pay all your subcontractors, laborers, and material suppliers. This is huge, as it prevents liens from being filed against the property.
This simple diagram shows the three-party relationship that makes every surety bond work.
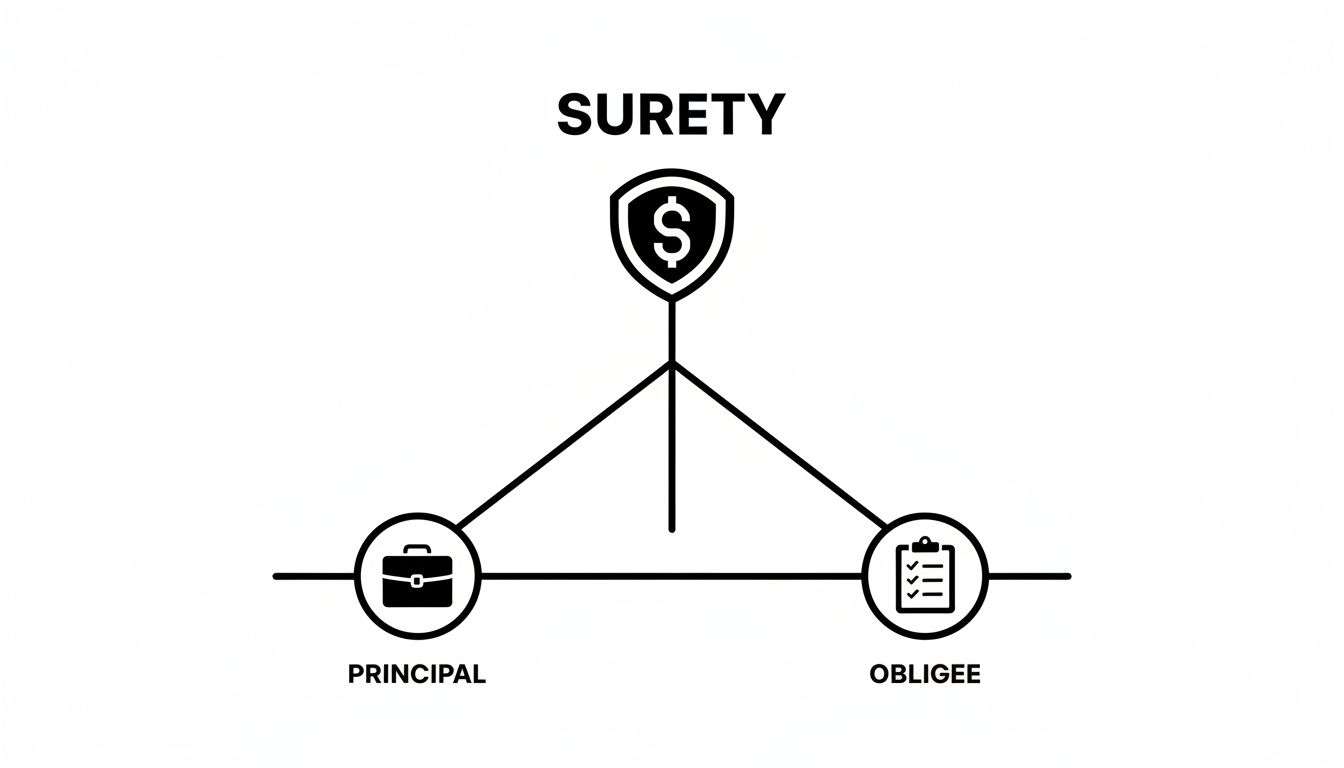
The Surety (the insurance company) provides a financial guarantee to the Obligee (your client) on behalf of you, the Principal. It’s all about creating a foundation of trust.
Understanding Commercial Bonds
While contract bonds are all about specific projects, commercial bonds cover a much wider range of businesses. Their main job is to ensure you follow all the federal, state, and local rules that apply to your industry.
For many businesses in Missouri and Kansas, getting bonded isn't a choice—it's a mandatory step to get your professional license.
A Commercial Bond is your public promise to operate ethically and by the book. It protects consumers and government agencies from fraud or bad practices.
Here are a few of the most common types you’ll run into:
- License & Permit Bonds: A huge number of professions need this bond to get or keep their license. For example, an auto dealer in Kansas City needs one to protect buyers from fraud. An electrician needs one to guarantee their work meets safety codes. The list of industries is long.
- Janitorial Service Bonds: This bond protects your clients from theft committed by your employees while on their property. It’s not always required by law, but having one is a powerful selling point that builds immediate trust and can help you win contracts over competitors.
- Probate Bonds (Fiduciary Bonds): A court requires this type of bond for people appointed to manage someone else's assets, such as the executor of an estate or a guardian. You can learn more about how a probate bond works in our detailed guide.
Whether you're a contractor bidding on a new school or an entrepreneur launching a cleaning service, the right bond builds credibility and helps you meet critical legal requirements. Here at Copeland Insurance Agency, our job is to help you find the exact bond you need so you can protect your clients and grow your business with confidence.
How Underwriters Evaluate Your Business for a Bond

Getting a surety bond feels a lot like applying for a business loan, and that’s no accident. The surety company isn't really concerned with on-the-job accidents; they are laser-focused on one thing: your ability to follow through on your promises. They are putting their own money on the line to guarantee your performance to your client.
Think of an underwriter as a careful investigator. Their job is to dig into your business and answer a single, critical question: Is this business strong and stable enough to get the job done right? To figure that out, they use a time-tested framework known as the "Three Cs" of underwriting.
The First C: Character
This one is all about reputation. Do you pay your bills? Do you have a history of integrity and finishing what you start? Underwriters want to see proof that you run an honest, responsible business.
Your personal credit score and the business's payment history with suppliers are huge here. A good name in the local Kansas City or Topeka business community also speaks volumes. It’s evidence that you’ve built trust over time, and that’s a powerful asset.
The Second C: Capacity
Capacity is about your ability to actually do the work. It’s not just wanting the job; it’s having the real-world resources to pull it off successfully.
An underwriter will look at several key areas to gauge your capacity:
- Experience: Have you and your key people tackled projects of this size and complexity before?
- Equipment: Do you own or have ready access to the machinery and tools needed to work efficiently?
- Labor: Is your team skilled and large enough to handle the project’s demands?
- Current Workload: What other jobs are you committed to? They need to know you aren’t spread too thin to give this new project the focus it needs.
For a surety, capacity is the proof in the pudding. It’s the difference between saying you can build a bridge and showing you have the engineers, equipment, and experience to actually do it.
A business that can clearly show its operational muscle is a far less risky bet for a surety company, making it easier to secure a small business bond insurance policy.
The Third C: Capital
Capital is the bottom line—your financial strength. The surety needs to be confident that your business has the cash flow to manage day-to-day costs, handle unexpected problems, and absorb any bumps in the road during the project. A healthy financial position is your ultimate safety net.
This is the most numbers-driven part of the whole process. Underwriters will ask for a specific set of financial documents to get a clear picture of your capital. Having these papers organized and ready to go is the single best thing you can do to speed up your bond approval.
Get ready to provide these documents:
- Business Financial Statements: This usually means a balance sheet and income statement for the last 2-3 years.
- Personal Financial Statements: Required from all business owners to show their individual financial stability.
- Work-in-Progress (WIP) Schedule: A must-have for contractors, this report details all your current projects, their status, and profitability.
- Bank Lines of Credit: Showing you have access to a credit line demonstrates you have a backup source of working capital if you need it.
By examining the Three Cs—Character, Capacity, and Capital—underwriters get a 360-degree view of your business. Here at Copeland Insurance Agency, we work with businesses all over Kansas and Missouri to help them present their strengths clearly. We'll walk you through the documentation so you can put your best foot forward and get the bond you need.
Understanding Bond Costs and the Claims Process
Whenever you’re looking at a new business requirement, two questions always jump out: "How much is this going to cost me?" and "What happens if something goes wrong?"
With small business bond insurance, the answers to these questions reveal a critical difference between a surety bond and a typical insurance policy. It's a distinction you absolutely need to understand.
Let's tackle the cost first. Your bond premium is the one-time fee you pay the surety company to issue their financial guarantee on your behalf. Unlike insurance premiums that can feel a bit abstract, a bond premium is refreshingly straightforward.
It’s calculated as a small percentage of the total bond amount you’re required to have.
For most standard surety bonds, you can expect the premium to be between 1% and 5% of the total bond value. A stronger financial profile often leads to a lower rate.
That percentage isn't pulled out of thin air. The surety underwriter sets your specific rate based on the "Three Cs" we talked about—your Character, Capacity, and Capital. A solid history of personal and business credit, a proven track record, and healthy business financials will almost always land you on the lower end of that range.
How a Surety Bond Claim Works
Now for the second, and arguably more important, question: What happens if a claim is filed? This is where the true nature of a surety bond—as a form of credit—comes into sharp focus.
A liability insurance policy pays a claim to protect you. A surety bond pays a claim to protect your client, and you are legally on the hook to pay that money back.
Think of the surety company as your financial backstop. They step in right away to make your client whole, but the financial responsibility ultimately circles right back to you, the principal.
Here’s a step-by-step look at how a typical claim unfolds:
- The Claim Is Filed: Your client (the obligee) believes you’ve failed to meet your contractual obligations. Maybe a project is unfinished or you haven't paid your suppliers. They file a formal claim against the bond directly with the surety company.
- The Surety Investigates: A surety doesn’t just cut a check on demand. They launch a thorough investigation to confirm the claim's validity, which includes getting your side of the story and all the relevant paperwork.
- A Resolution Is Reached: If the investigation proves the claim is valid, the surety will work to resolve it. This could mean paying another contractor to finish the job or settling debts with your suppliers, up to the full bond amount.
- The Principal Reimburses the Surety: This is the key. Under the indemnity agreement you signed to get the bond, you are legally obligated to repay the surety for every dollar they paid out, including the claim itself and any legal fees they incurred.
An Advocate in Your Corner
Facing a claim can be a stressful and confusing process. That’s exactly why having an expert in your corner is so valuable.
At Copeland Insurance Agency, we don't just sell you a bond and wish you luck. We act as your advocate, helping you navigate the process and communicate effectively with the surety if a claim ever arises. Our job is to provide guidance and support right when you need it most.
Understanding the fine print of any business coverage is always important. For instance, digging into the details of Motor Truck Cargo Insurance requires a similar deep dive into its unique costs and claims process. With surety bonds, the main thing to remember is that they are a powerful tool for building trust, but they come with a serious financial responsibility you must be prepared to honor.
How to Get a Surety Bond: A 4-Step Walkthrough

Knowing you need a bond is one thing. Actually getting one can feel like a totally different beast, especially when you’re staring down a mountain of unfamiliar forms and industry jargon.
The good news? It doesn't have to be a headache. With the right partner guiding you, the process is surprisingly straightforward. This is your roadmap to getting the exact bond you need, without the usual runaround.
At Copeland Insurance Agency, we’ve spent years refining this process to get the right documents into your hands fast. We believe securing small business bond insurance should be a clear, manageable path—not another source of stress. Our deep roots in Kansas and Missouri mean we know the local landscape and the specific bond requirements you’ll face.
Here’s a look at our four-step process, designed to cut through the complexity so you can focus on what you do best: running your business.
Step 1: The Initial Consultation and Needs Analysis
It all starts with a simple conversation. Our first job is to get a solid understanding of your business and what you need right now. Are you a contractor in Wichita bidding on a new city project? A car dealer in Kansas City who needs a license bond to operate? Every detail matters.
During this first chat, we’ll nail down:
- The specific bond type your client or the government agency (the obligee) is asking for.
- The exact bond amount, also called the "penal sum," needed to satisfy your contract or license.
- The details of the project or obligation so we can anticipate any special requests from the surety.
This first step is crucial. By getting these details right from the very beginning, we head off potential delays and make sure you’re applying for the correct guarantee from the start.
Step 2: The Guided Application and Paperwork
Once we know exactly what you need, it’s time to put together a strong application for the underwriters. This is where we translate your business’s strengths—your Character, Capacity, and Capital—into the language that surety companies understand. You will absolutely not be left alone to figure out confusing forms.
Our team will walk you through gathering the necessary documents, which often include:
- A completed bond application.
- Your business and personal financial statements.
- Information on your relevant experience in the industry.
- For contractors, a Work-in-Progress (WIP) schedule.
Think of this step as building your case. A well-organized, complete application demonstrates professionalism and financial responsibility, directly influencing your approval and the premium you'll pay.
We’re here to help you present your information in the best possible light, making a powerful impression on the surety underwriter.
Step 3: Finding the Right Surety Carrier
Not all surety companies are created equal. Some focus on specific industries, while others might be a better fit for new businesses or those with a unique financial picture. As an independent agency, we aren't tied to any single carrier—and that freedom is your biggest advantage.
We tap into our extensive network of surety partners to find the perfect match for your specific situation. This means we shop around for you, hunting down the best possible terms and rates. Our long-standing relationships with carriers across the region allow us to be your strongest advocate.
Step 4: Bond Issuance and Delivery
Once a surety approves your application and you’ve paid the premium, the final step is getting that bond in your hands. We make sure the official documents are executed perfectly and delivered to you—or sent directly to the obligee—without a moment's delay.
We get it. Time is almost always a factor. Whether you have a hard deadline to submit a bid or you need a license to open your doors, we make speed and accuracy our top priorities. Our team handles all the final details so you can get your bond and move forward with confidence, ready to lock in that next opportunity.
Your Questions About Small Business Bonds Answered
Here at Copeland Insurance Agency, we’ve guided countless businesses across Kansas and Missouri through the bonding process. After all these years, we’ve found that the same handful of questions come up time and time again. Let’s get you the clear, straightforward answers you need to land your next big opportunity with confidence.
How Is a Surety Bond Different from General Liability Insurance?
This is easily the most common point of confusion we see, and getting it right is crucial. General liability insurance is there to protect your business from claims made by others, like if someone gets hurt on your job site or you damage their property. It's a classic two-party agreement between you and your insurer to manage your own financial risks.
A surety bond, on the other hand, is a three-party agreement that protects your client (the obligee). It's a guarantee you’ll get the job done right and meet all your financial obligations. Think of it like this: insurance protects you from your mistakes, but a small business bond insurance policy protects your client from your failure to follow through.
The simplest way to remember it is: Insurance is for you; a bond is for them. This single difference is why clients often require you to have both.
Can I Get a Bond if I Have a New Business or Past Credit Issues?
Yes, it's often possible—so don't count yourself out. While a long, stable business history and a strong credit score are definitely a plus, they aren't the whole story. Surety companies also put a huge emphasis on your character and, most importantly, your hands-on experience in your industry.
For new businesses or those working to rebuild their credit, specialized surety markets exist that offer more flexibility. This is where being an independent agency like Copeland really helps our clients. We have relationships with a wide range of carriers and know which ones are best suited for different situations, allowing us to build a strong case for you by highlighting your expertise and track record.
How Long Does It Typically Take to Get a Surety Bond?
The timeline really depends on the bond's type and how complex it is. The good news is that many simpler, standard bonds can be turned around very quickly.
- License and Permit Bonds: These are common, standardized, and can often be approved and issued within 24-48 hours.
- Contract Bonds: For larger or more complicated projects, the underwriting is naturally more in-depth. This process can take anywhere from a few days to a week.
Without a doubt, the single biggest factor in speeding things up is being prepared. Having your application and all the necessary financial documents ready to go from the start is the best way to avoid delays. Our team walks you through exactly what's needed ahead of time to make sure the process is as smooth as it can be.
What Happens if Project Requirements Change After the Bond Is Issued?
Scope creep is a reality, especially on bigger jobs. If the contract value goes up or the work you're doing changes in a major way, you need to let us know immediately. A change order from your client will likely require a "rider" or an "increase in penalty" for your bond.
Ignoring these changes is a big risk. It can put you out of compliance with your contract and leave your client under-protected, which could even void the bond. Proactive communication is the key. We'll work directly with the surety company to make the necessary adjustments, ensuring your bond coverage stays adequate and everyone remains protected as the project moves forward.
Secure Your Next Opportunity with the Right Partner
We've covered a lot of ground, from what small business bond insurance is to the different types you might need. The big takeaway? A surety bond isn't just a hoop to jump through—it's a powerful tool that proves your credibility, builds trust, and ultimately unlocks bigger and better opportunities for your business.
Since 1960, Copeland Insurance Agency has been the go-to partner for businesses all across Kansas and Missouri, helping them navigate these exact requirements. We're not just a faceless company; we're your neighbors, and we bring decades of local expertise to the table because we live and work here, too.
Your Local Partner from Kansas City to Rural Kansas
Whether you’re a general contractor in Kansas City eyeing a major public works project or a specialty trade in a small rural town needing a license bond, we've been there. We know the landscape. Our job is to cut through the jargon and translate the complex world of sureties into clear, practical advice you can act on.
A surety bond isn’t an obstacle—it’s a declaration of your commitment to quality and integrity. It tells your clients, partners, and community that you are a business they can count on to deliver on your promises.
Working with an independent agency like ours means you have a true advocate in your corner. We tap into our extensive network of top-rated surety carriers to find the right fit for you, securing favorable terms and premiums so you can stay focused on what you do best.
Don't let a bond requirement be the one thing standing between you and your next big win.
Let's Build Your Future Together
Getting started is simple. We believe in making the bonding process as painless as possible. Our team is ready to sit down with you for a no-obligation consultation, answer any lingering questions, and map out a clear path forward.
You can get in touch through our online service center or by calling one of our local offices right here in Kansas. We're here to give you the support you need to get your bond in place quickly and confidently.
Don't let a bond requirement slow you down. Copeland Insurance Agency is ready to help you get the credentials you need to win the job. Request a quote online today and let's get started.