

Personal umbrella policy: Essential 2025 Security
Why a Personal Umbrella Policy Could Be Your Best Financial Decision
A personal umbrella policy provides an essential layer of extra liability coverage that activates when your standard home, auto, or other insurance policies have reached their maximum limits. In an increasingly litigious world, understanding this coverage is more critical than ever. Here’s what you need to know:
Quick Facts:
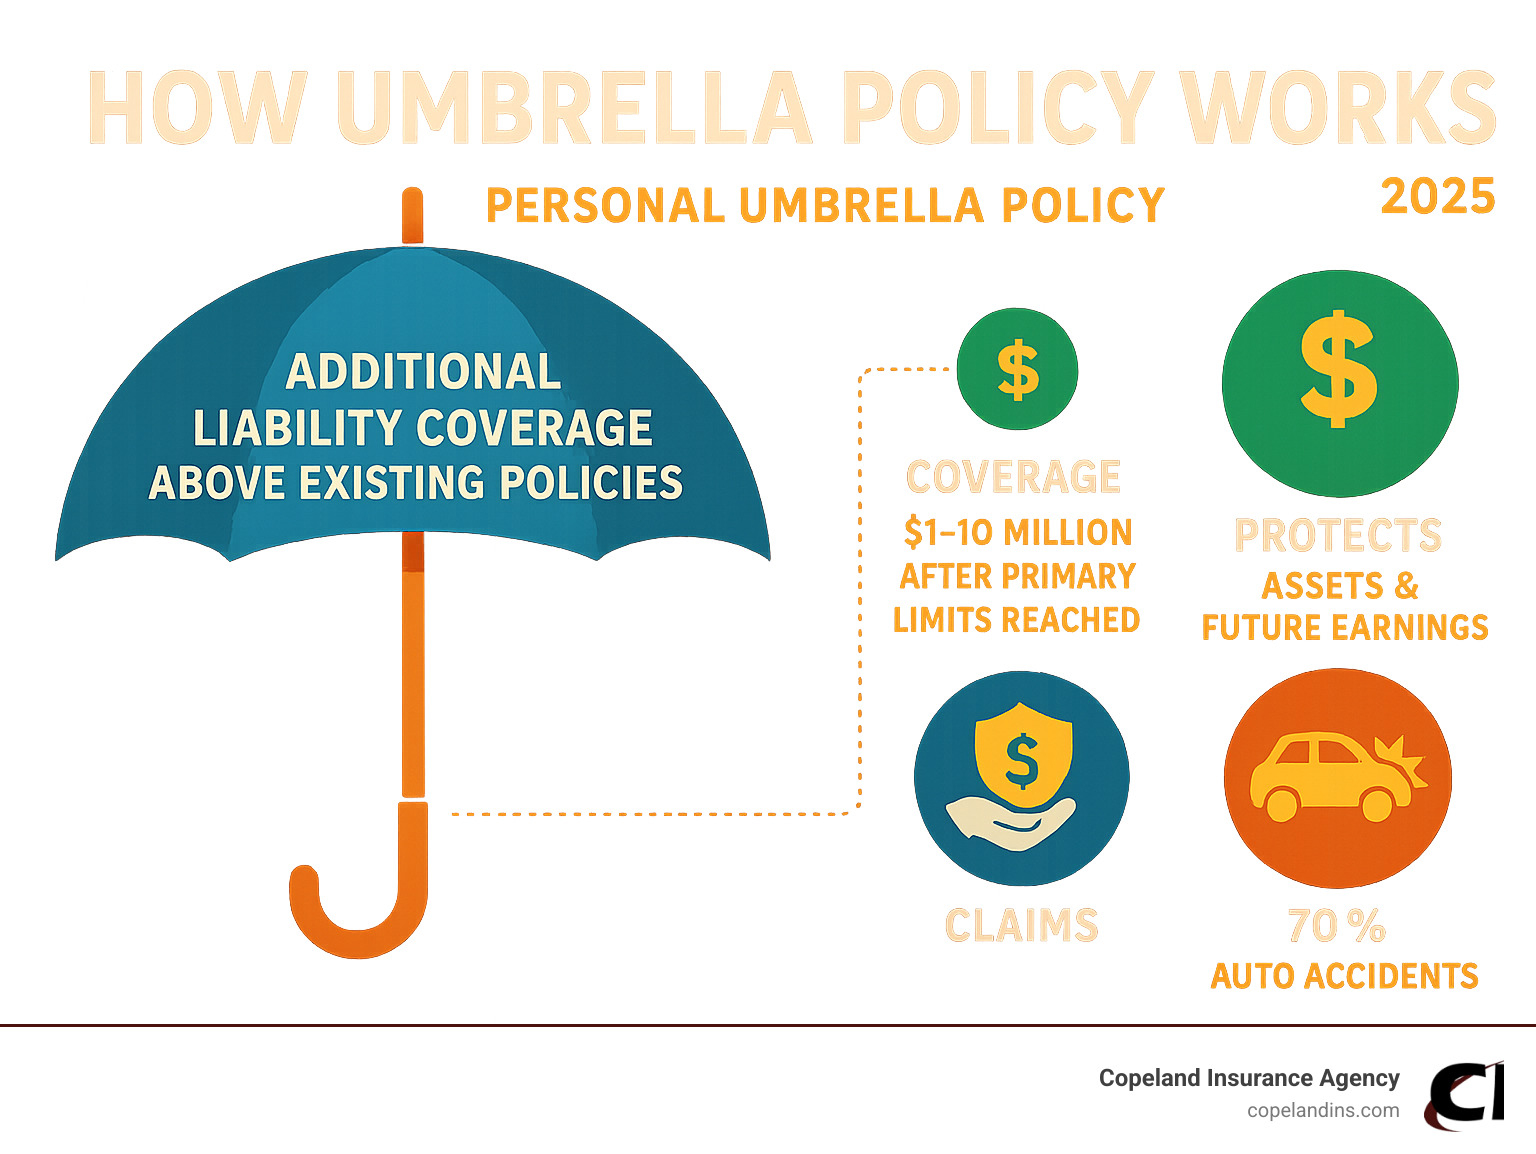
- What it is: It is additional liability insurance that sits ‘above’ your existing policies, acting as a crucial second line of defense.
- Coverage: You can typically secure between $1 million and $10 million in protection, with entry-level policies starting at a surprisingly affordable $200-300 annually.
- Purpose: Its primary goal is to protect your hard-earned assets and, just as importantly, your future earnings from the devastating financial impact of costly lawsuits.
- Claims: A staggering 70% of umbrella claims are auto-related, a statistic fueled by the rise of distracted driving and increasingly severe accidents.
Life is unpredictable. Sometimes things go wrong – a momentary lapse in attention on the road, a guest slipping on your property, a comment online taken the wrong way, or an unexpected lawsuit. Without the right level of coverage, a single unfortunate event can completely compromise your financial security, solveing years of hard work and careful planning.
One lawsuit can change everything. Imagine a legal judgment against you that far exceeds the liability limits on your standard auto or homeowners policy. In that scenario, your personal assets-your home, your savings, your investments, your retirement funds-and even your future earnings become vulnerable to seizure or garnishment. An umbrella policy acts as a powerful financial safety net, covering the massive costs of legal fees, court judgments, and settlement damages that could otherwise be financially devastating and life-altering.
It’s a common misconception that you are safe from legal action if you’ve done nothing wrong. The reality is that anyone can face a lawsuit, regardless of fault. Whether you have already accumulated significant assets to protect or are just at the beginning of your journey to build wealth, umbrella coverage offers affordable and profound peace of mind.
With over two decades of dedicated insurance experience, the team at Copeland Insurance Agency has witnessed how a personal umbrella policy can be the critical factor that protects families from financial ruin. We have guided countless clients through the process of making these crucial coverage decisions, helping them secure their financial futures against the unexpected.
What is a Personal Umbrella Policy and How Does It Work?
Think of your standard home and auto insurance as a reliable raincoat-it provides adequate protection for most everyday showers. A personal umbrella policy, however, is your shelter in a financial hurricane. It is designed to provide massive, essential coverage when the storm of a major liability claim proves too powerful for your standard protection.
A personal umbrella policy is a form of excess liability insurance. It does not stand alone; instead, it sits on top of your existing coverage, such as your auto, home, or boat insurance. While your standard policies have liability limits-for instance, $250,000 or $500,000-an umbrella policy adds a substantial extra layer of protection, often providing an additional $1 million or more in coverage.
Here is why that matters: when someone successfully sues you for an amount greater than what your basic policy covers, you are personally on the hook for the difference. This can put everything you own and everything you will earn at risk. Your savings, your home, your retirement accounts, and even your future wages could be targeted to satisfy the judgment. With umbrella coverage, that extra protection kicks in to cover what your primary policies cannot, shielding you from financial catastrophe.
For example, let’s imagine a scenario where you cause a serious car accident. The resulting judgment against you for medical bills, rehabilitation, lost income, and pain and suffering totals $1.2 million. If your auto insurance policy has a liability limit of $500,000, your insurer pays that amount, but you would still be personally responsible for the remaining $700,000. A personal umbrella policy would step in to handle that enormous difference, protecting your financial future from being derailed by one tragic event.
To better understand your existing protection, check out our resources on auto insurance and home insurance.
| Feature | Standard Liability Insurance (Auto/Home) | Personal Umbrella Policy |
|---|---|---|
| Coverage Types | Bodily Injury, Property Damage | Bodily Injury, Property Damage, Personal Injury (libel, slander, privacy invasion) |
| Coverage Limits | Typically lower (e.g., $250K-$500K) | Much higher (e.g., $1M-$10M+, sometimes up to $100M) |
| Cost | Included in primary policy premium | Separate, often very affordable annual premium |
| Trigger | Primary cause of action | Kicks in after primary policy limits are exhausted or for claims not covered by primary policies |
| Scope | Specific to the insured item (car, home) | Broad, covers multiple aspects of your personal life, often worldwide |
How an Umbrella Policy Complements Your Existing Insurance
Your underlying policies for your car, home, or boat are your essential first line of defense. A personal umbrella policy does not replace them; it improves them, acting as a critical backup plan for major, high-cost liability events. When a covered incident occurs, your primary insurance policy is the first to respond. It handles the claim up to its defined limits. Once those limits are reached, or ‘exhausted’, your umbrella policy seamlessly takes over, preventing a dangerous gap in coverage that could expose your personal assets.
This comprehensive protection includes bodily injury liability, which covers others’ medical expenses, lost wages, and compensation for pain and suffering. It also includes property damage liability, which pays for damage to another person’s property, such as their vehicle or home. Whether you are at fault in a multi-car accident or a guest suffers a serious injury on your property, you are protected from the immense financial fallout.
The claim process is designed to be straightforward. It always starts with your underlying policy. Once that policy’s limits are fully paid out, your umbrella coverage is triggered to handle the excess amounts, ensuring you are not left facing devastating out-of-pocket expenses that could take a lifetime to pay off.
For more detailed information about this additional layer of protection, visit our page on excess liability insurance.
Key Features and Benefits
Beyond simply offering higher liability limits, a personal umbrella policy provides a range of practical features that are incredibly valuable in today’s complex world.
Worldwide coverage is a significant benefit. It protects you not just at home but also when you are traveling abroad. If you rent a car in Europe and have an accident, or if an incident occurs while you are on vacation in another state, your umbrella policy has you covered, providing a consistent shield of protection wherever you go.
A key and often overlooked benefit is coverage for defense costs and legal fees. The cost of defending against a lawsuit can be financially crushing, even if the suit is frivolous and you are ultimately found not liable. Your umbrella policy typically covers these costs from the beginning, outside of your liability limit, preserving your policy’s full power for potential settlements or judgments. This includes providing a robust defense against false or fraudulent lawsuits.
The coverage also extends to a category of risk known as personal injury. This goes beyond physical harm to cover claims like libel and slander (written or spoken defamation), false arrest, malicious prosecution, or invasion of privacy. In our hyper-connected social media age, a hastily written negative online review or an ill-conceived comment on a community forum could easily lead to a costly defamation lawsuit. Your umbrella policy can handle the legal defense and potential damages, even for claims that are ultimately proven to be groundless.
Perhaps the greatest benefit of all is the profound peace of mind it provides. Knowing that your assets, your savings, and your future earnings are protected from life’s most unexpected and severe events is an invaluable feeling. It is an affordable layer of protection that can prevent one single incident from derailing your financial future and the life you have worked so hard to build.
What’s Covered and What’s Excluded?
Understanding the specific scope of what a personal umbrella policy covers-and just as importantly, what it does not-is crucial for making intelligent insurance decisions and avoiding unwelcome surprises when you need your coverage the most. This policy is broad, but it has clearly defined boundaries.

The scene above depicts a high-cost liability event where a personal umbrella policy transforms from a theoretical safety net into a tangible financial lifeline. When multiple vehicles and serious injuries are involved, the associated costs for medical care, long-term rehabilitation, and legal damages can quickly spiral into the millions. Your umbrella policy is designed to step in precisely when your regular auto insurance limits are exhausted by such a catastrophic event.
At its core, your umbrella policy is designed to protect you when you are found legally responsible for causing bodily injury or property damage to other people. It also extends its shield to cover certain personal injury claims, which are offenses that can damage someone’s reputation, character, or invade their personal privacy.
Incidents Typically Covered by an Umbrella Policy
A personal umbrella policy truly shines during life’s most stressful and financially threatening moments. Here is a more detailed look at the common scenarios where it comes to your rescue:
- Serious auto accidents: This is the most frequent trigger for umbrella claims, accounting for a remarkable 70% of them. When a major accident results in severe injuries or fatalities, the ensuing medical bills, lost wages, and pain and suffering awards can easily surpass the limits of even a robust auto insurance policy. Your umbrella policy covers the difference, preventing financial ruin.
- Guest injuries on your property: Imagine you are hosting a backyard party and a guest falls from a faulty deck, suffering a permanent injury. You could face a lawsuit seeking massive damages for medical expenses, ongoing care, and lost quality of life. Your homeowners insurance covers the first portion of the claim, and your umbrella policy handles the rest, potentially saving you from losing your home.
- Dog bites: As a pet owner, you are legally responsible for your dog’s actions. Dog bite claims can be surprisingly costly, often involving plastic surgery and psychological trauma. An umbrella policy provides critical liability coverage that extends far beyond your home policy’s typical limits for such incidents.
- Libel or slander: In our digital age, this risk is more prevalent than ever. A negative online review of a local business, a heated comment on a community Facebook page, or a post about a neighbor could lead to a lawsuit alleging defamation. Your personal umbrella policy can cover the substantial legal defense costs and any resulting judgments for written (libel) or spoken (slander) defamation.
- Defamation of character and invasion of privacy: Sharing a photo or story on social media that someone claims damaged their reputation or violated their privacy can have expensive legal consequences. These non-physical injuries are often specifically covered by an umbrella policy’s personal injury protection.
- Rental property liability: If you are a landlord, you face liability risks from your tenants and their guests. A slip-and-fall on an icy walkway or an injury caused by a property maintenance issue can lead to claims that exceed your landlord insurance limits. An umbrella policy provides an essential extra cushion of protection for your investment properties.
- Liability while volunteering: If you coach a youth sports team or serve on the board of a non-profit, you could be held personally liable for injuries or decisions made in your volunteer capacity. An umbrella policy can provide coverage for these activities.
Common Exclusions to Be Aware Of
An umbrella policy is not a magic wand that covers every possible problem. Understanding its exclusions is key to ensuring you have a complete and gap-free insurance portfolio.
- Your own injuries: Umbrella insurance is liability coverage; it protects you from claims made by others. Your own medical needs would be covered by your health insurance, and injuries from a car accident would be covered by your auto policy’s medical payments or personal injury protection.
- Damage to your personal property: Damage to your own home, car, or belongings is covered by your dedicated homeowners or auto insurance policies, not your umbrella policy.
- Business-related losses: This is a personal umbrella policy, meaning it explicitly excludes liability arising from your business operations or professional services. You will need separate commercial general liability and professional liability insurance to cover claims related to your business.
- Intentional or criminal acts: Insurance is designed to cover accidents and negligence, not deliberate harm. If you intentionally injure someone or damage their property, your policy will not cover you. The financial and legal consequences are your own to bear (though some policies may provide a defense for claims of self-defense until it is proven otherwise).
- Punitive damages: In some legal cases, courts award punitive damages, which are intended to punish the defendant for particularly reckless or egregious behavior, such as driving under the influence. While your umbrella policy typically covers compensatory damages (meant to make the injured party whole), coverage for punitive damages is often excluded and may be prohibited by state law.
Who Needs Umbrella Insurance and How Much is Enough?
The single biggest myth about personal umbrella policies is that they are a luxury product reserved only for the very wealthy. The truth is, if you have any assets to protect-or more importantly, if you have future income you want to safeguard-you should seriously consider this essential coverage. One major lawsuit has the power to erase decades of hard work and savings, regardless of your current net worth.

This family’s backyard contains what insurers refer to as ‘attractive nuisances.’ A swimming pool and a trampoline, while sources of fun, significantly increase the risk of a guest (especially a child) being injured on your property. This heightened liability risk makes umbrella coverage especially valuable. At Copeland Insurance Agency, we help families in Kansas, Arizona, and Texas understand a simple principle: if you own a home, have savings, invest for retirement, or earn a decent living, you have a financial future that needs this level of protection.
The National Association of Insurance Commissioners explains that umbrella policies provide coverage for liability and defense costs your primary insurance doesn’t cover. You can learn more at What’s an Umbrella Policy?. For homeowners, we offer detailed guidance at More info on Umbrella Insurance for Homeowners.
Assessing Your Personal Risk Factors
Your lifestyle and assets create a unique risk profile. The more of these common risk factors you have, the more crucial a personal umbrella policy becomes for your financial security:
- Teenage drivers: With 70% of umbrella claims stemming from auto accidents, having a young, inexperienced driver in the household is one of the single largest liability risks a family can have. Their lack of experience dramatically increases the chance of a serious at-fault accident.
- Pet ownership: Dog bites can lead to claims averaging tens of thousands of dollars, and sometimes much more. Your umbrella policy provides coverage when your homeowners liability limits are not sufficient to cover the medical bills and legal damages.
- Significant social media activity: Your words can have expensive consequences. A negative online review, a critical blog post, or a comment on a community forum could spark a defamation (libel or slander) lawsuit. Umbrella policies are one of the few personal insurance products that cover these modern risks and the associated legal defense costs.
- Volunteer work and serving on boards: If you coach a youth sports team or serve on a homeowners association (HOA) board, your decisions and actions could expose you to personal liability claims. Umbrella insurance can protect you in these roles.
- Watercraft ownership: Boating and jet ski accidents can cause severe injuries and extensive property damage, creating a significant liability risk that can easily exceed the limits on a standard boat insurance policy.
- Rental property ownership: As a landlord, you are a prime target for tenant-related lawsuits. An umbrella policy provides a vital layer of protection over your landlord policy, safeguarding your personal assets from claims arising from your rental properties.
Choosing Your Coverage Limits
So, how much coverage do you actually need? The process begins with a clear-eyed assessment of your net worth. You need to calculate everything a court could potentially take from you in a major lawsuit. This includes your home equity, savings accounts, non-retirement investments, retirement funds, and, critically, your future earning potential.
- $1 million coverage is the typical starting point and the most common policy limit. It provides a substantial amount of protection and is surprisingly affordable, often costing around $200-$300 annually.
- Higher limits of $2 million to $10 million are a wise investment for individuals with substantial assets, high incomes, or significant risk factors (like multiple rental properties or teenage drivers). The cost to increase coverage is incremental; doubling your protection from $1 million to $2 million often costs only slightly more per year.
- Asset valuation is the foundation of this decision. Create a simple balance sheet. List your assets: real estate equity, brokerage accounts, savings, 401(k)s, IRAs, and valuable personal property. Many people significantly underestimate their net worth and, therefore, their exposure.
- Future income protection is absolutely critical, especially for younger professionals and high earners. A large judgment can result in wage garnishment for years or even decades. An umbrella policy protects not just what you have today, but also the income you expect to earn tomorrow.
The exceptional cost-to-protection ratio makes umbrella insurance one of the single best values in the entire personal insurance market.
For more information, the Massachusetts government provides helpful guidance: Personal Umbrella and Excess Liability Insurance information.
The Nuts and Bolts: Requirements and Costs
Many people incorrectly assume that securing a personal umbrella policy is a complicated or expensive process, reserved for financial experts or the ultra-wealthy. The opposite is often true. At Copeland Insurance Agency, we consistently find that our clients are pleasantly surprised by how straightforward and remarkably affordable this crucial layer of protection is.

Think of an umbrella policy as adding a second story to your financial house-you must have a solid foundation in place first. In this analogy, that foundation is adequate liability coverage on your existing auto and home insurance policies. Insurers require this foundation so that your underlying policies are equipped to handle the first layer of any claim. This structure ensures the umbrella is reserved for its intended purpose: shielding you from true financial catastrophes.
The underwriting process is typically smooth and efficient for our clients in Manhattan, Abilene, Junction City, and our other service areas in Kansas, Arizona, and Texas, especially if they already maintain good liability limits on their primary policies. Most applicants find they either already meet the requirements or that only minor, inexpensive adjustments are needed to their existing coverage. For more on all your personal insurance options, visit our More info on Personal Insurance page.
Prerequisites for Getting a Personal Umbrella Policy
Before an insurance company will issue an umbrella policy, they need to verify that you have a robust level of liability coverage on your underlying policies. This requirement is not meant to be a barrier; it is essential to the function of the product. It ensures the umbrella works as intended, stepping in only after your primary coverage has been exhausted.
- Auto insurance: Most insurers require minimum liability limits of $250,000 per person and $500,000 per accident for bodily injury, plus at least $100,000 for property damage. These are often abbreviated as 250/500/100.
- Homeowners insurance: You will typically need to have at least $300,000 in personal liability coverage on your home, condo, or renters insurance policy. Some carriers may require up to $500,000.
- Other policies: If you own recreational vehicles like boats, RVs, or motorcycles, you will need to carry appropriate liability coverage on those policies as well, as they represent additional sources of risk.
Bundling policies with the same insurer that provides your home and auto insurance is often the most logical and beneficial approach. It can lead to significant discounts on all your policies and, more importantly, it dramatically simplifies the claims process. In the event of a major claim, you will have one company and one agent handling everything seamlessly, preventing potential conflicts or delays between different carriers.
Understanding the Cost of a Personal Umbrella Policy
Here is the pleasant surprise for most consumers: a personal umbrella policy with $1 million in additional protection typically costs just $200 to $300 annually. That breaks down to less than a dollar a day for a level of financial security that can protect you from losing everything.
The average premium is so low because the catastrophic claims that trigger these policies, while devastating, are infrequent from an actuarial standpoint. The cost per million dollars of coverage often decreases as you purchase higher limits. For example, increasing your coverage from $1 million to $2 million might only add another $50 to $75 to your annual premium. This makes higher limits of $2 million to $10 million an incredibly attractive value for those with more assets or risks to protect.
Several factors influence your premium. The most significant are your personal risk factors, including your household’s driving record, the presence of teenage drivers, and property risks like swimming pools, trampolines, or certain dog breeds. The number of homes, vehicles, and recreational vehicles you own will also be considered. In some states, your credit history may also be used as a rating factor. For a small annual investment, you can effectively safeguard the assets you have spent a lifetime building.
Frequently Asked Questions
At Copeland Insurance Agency, we believe that a well-informed client is a well-protected client. We hear these questions all the time, so let’s clear up some of the most common points of confusion and misconceptions surrounding personal umbrella policies.
Do I still need an umbrella policy if I don’t have a lot of assets?
Yes, absolutely! This is the most common and dangerous myth about umbrella insurance. A personal umbrella policy protects something that can be even more valuable than your current assets: your future earnings. If you lose a major lawsuit and do not have enough insurance to cover the judgment, courts can order wage garnishment. This is a legal process where a portion of every paycheck you earn is automatically diverted to the plaintiff to satisfy the debt. This can follow you for years, or even decades, severely impacting your ability to save, invest, and build the life you are working toward.
If you have a job and the potential to earn income in the future, you have something incredibly valuable that is at risk. An umbrella policy safeguards your long-term financial security and your future lifestyle, regardless of how much you have in the bank today.
Does my umbrella policy cover me when I travel?
Yes, in most cases, your personal umbrella policy provides worldwide coverage. This is a fantastic and often underappreciated feature that sets it apart from many basic insurance policies. This global protection provides an extra layer of security no matter where life takes you.
For example, if you are vacationing in another country and rent a car, the liability insurance included with the rental or required by local law may be extremely low. If you cause a serious accident, you could be exposed to a massive lawsuit in a foreign legal system. Your umbrella protection travels with you, ready to step in above the local policy limits. This is invaluable peace of mind for anyone who travels internationally or even just outside their home state.
Can I get a standalone umbrella policy?
While it is sometimes possible to purchase a standalone policy from a specialty insurer, we generally do not recommend it, and most standard insurance companies do not offer them. The vast majority of insurers require you to have your underlying auto and homeowners policies with them before they will sell you an umbrella. They do this because they need to ensure you meet their minimum liability limits and so they can get a full picture of the risks they are covering.
This approach usually works out much better for you, the client. The bundling benefits often include significant premium discounts on all your policies and lead to a much simpler and more efficient claims process. At Copeland Insurance Agency, we find that clients who bundle their auto, home, and umbrella coverage typically receive better service and overall value. However, we will always work with you to find the best solution for your unique needs.
What is the difference between an umbrella policy and excess liability insurance?
These terms are often used interchangeably, but there can be a subtle difference. ‘Excess liability’ is a broad term for any policy that provides limits above an underlying policy. A ‘true follow-form excess’ policy does exactly that and nothing more-it provides higher limits but covers the exact same things as the policy beneath it. A personal umbrella policy is a specific type of excess liability that not only adds higher limits but also broadens coverage. For example, it often covers risks that your home or auto policy might not, such as personal injury claims like libel, slander, or false arrest. For personal insurance, the vast majority of policies sold are true umbrella policies.
How does the claims process work with an umbrella policy?
The process is designed to be seamless. First, you report the incident to your primary insurer (e.g., your auto insurance company for a car accident). You should also notify your umbrella insurer that a claim has occurred that has the potential to exceed your primary limits. Your primary insurer will then manage the claim, providing a legal defense and paying up to their policy limit. If the final settlement or court judgment is higher than that limit, the umbrella insurer steps in to pay the remaining amount, up to the limit of the umbrella policy itself.
Protect Your Future with the Right Coverage
Financial security is built on careful planning and diligent work, but it can be shattered in an instant by a single, unforeseen event. A personal umbrella policy is your financial safety net, an essential shield designed to catch the catastrophic liability costs that could otherwise devastate your family’s future. For what often amounts to less than a dollar a day, you can secure millions of dollars in protection for your home, your savings, and all of your future earnings.
Throughout this guide, we have walked through how an umbrella policy complements your existing insurance, providing a second, more powerful layer of defense. We have explored the wide range of incidents it covers, from the most common auto accidents to modern digital risks like libel and slander. Whether you have teenage drivers, own rental properties, enjoy boating, or simply want to safeguard the assets you have worked your entire life to build, this coverage is one of the smartest and most cost-effective additions you can make to your financial plan.
The peace of mind alone is invaluable. Knowing that you and your family are protected from the financially crippling effects of a major liability claim allows you to live more confidently and with less worry about the ‘what ifs’ of life.
At Copeland Insurance Agency, we believe in building relationships and protecting the life you have built. With offices serving Kansas communities like Manhattan, Abilene, and Junction City, and with our expanded reach into Arizona and Texas, we are here to provide the expert advice and personal attention you deserve.
Don’t wait for a ‘what if’ moment to become a devastating reality. The best time to secure umbrella coverage is long before you need it. Protecting your family’s future is one of the most important financial decisions you will ever make. An umbrella policy is not a luxury; it is a fundamental component of a sound financial defense. Let us help you evaluate your unique risks and find a personal umbrella policy that fits your needs and your budget.
Ready to take this important step? Get Liability Insurance Online Quotes and find just how affordable comprehensive protection can be.