

Liability Insurance for Wedding Planners: Secure Your 2025
Why Wedding Planners Need Liability Protection
Liability insurance for wedding planners protects your business from costly lawsuits and claims that can arise from accidents, mistakes, or injuries during events. Here’s what you need to know:
Essential Coverage Types:
- General Liability – Covers guest injuries and property damage at events
- Professional Liability (E&O) – Protects against claims of errors or service failures
- Commercial Property – Covers your business equipment and office space
- Cyber Liability – Protects client data from breaches and cyber attacks
Key Benefits:
- Legal defense costs covered (can exceed $50,000 alone)
- Venue requirements met with Certificate of Insurance (COI)
- Professional credibility with clients and vendors
- Annual policies start as low as $8.25 per month
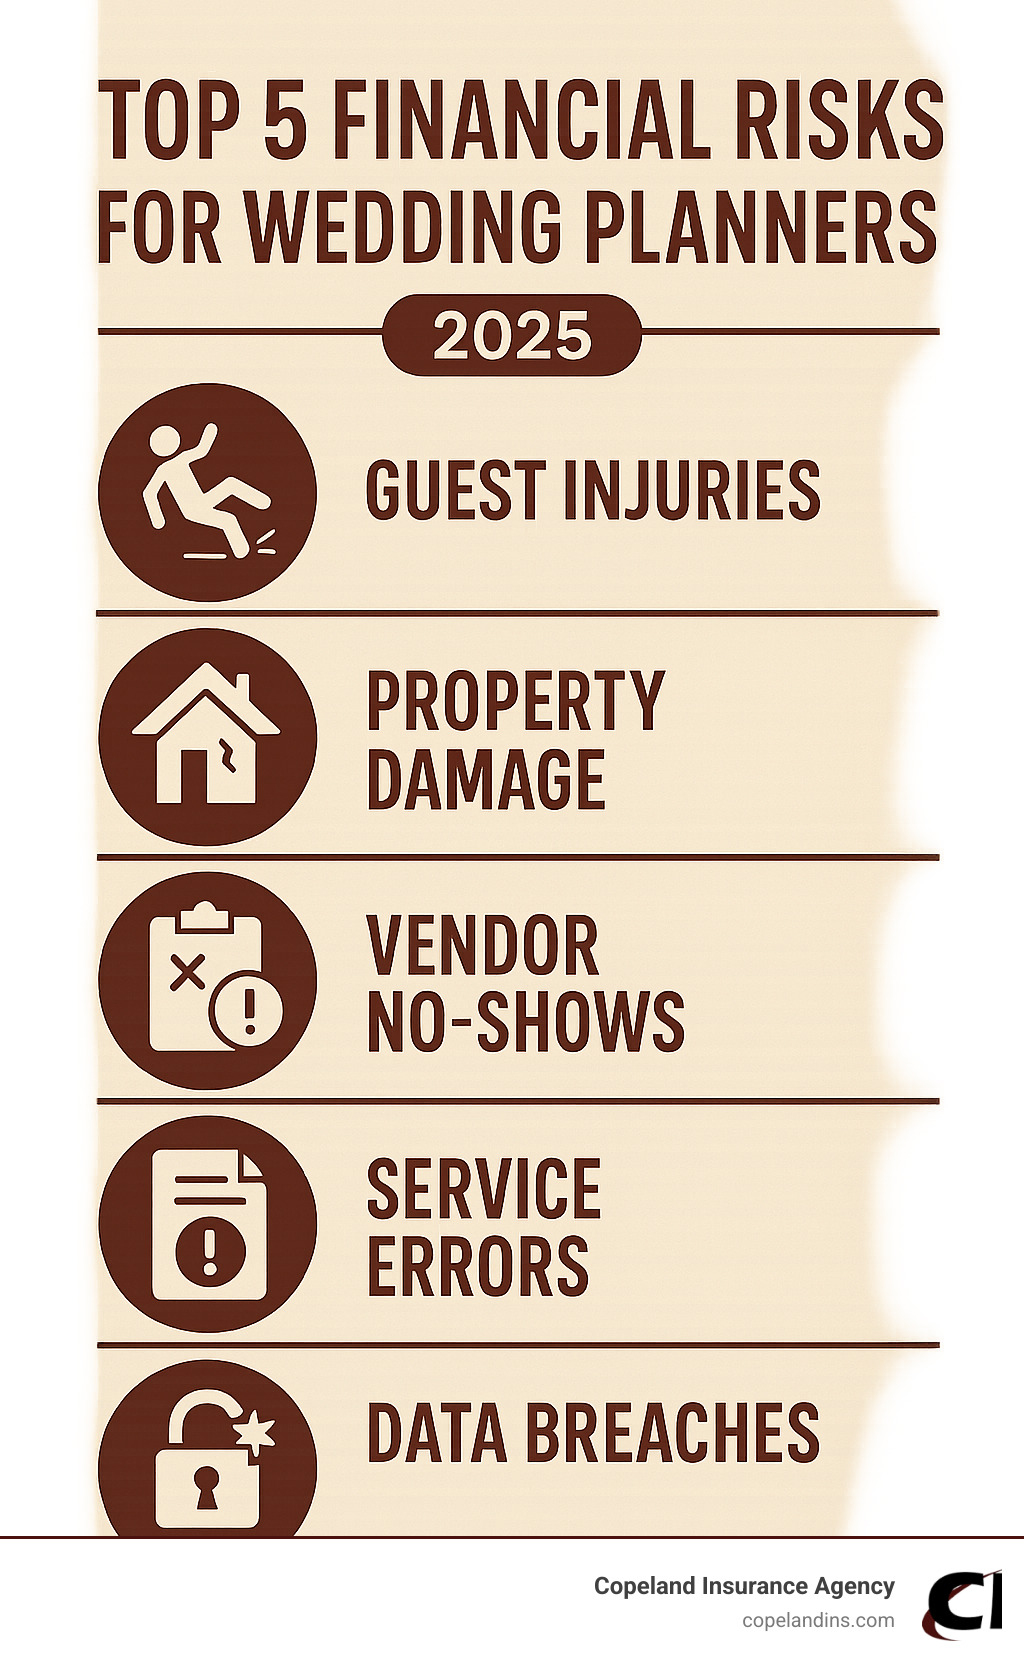
Wedding planning involves countless moving parts – from coordinating vendors to managing guest safety. A single guest injury or vendor mistake can result in devastating financial consequences for your business. Even the most careful planners face risks like guests tripping over equipment cords, venue property damage, or vendor no-shows that lead to client lawsuits.
Most wedding venues now require planners to carry liability insurance and provide a Certificate of Insurance before allowing access to their facilities. This requirement isn’t just paperwork – it’s recognition that wedding planning carries real financial risks that need professional protection.
With over two decades in the insurance industry, Copeland Insurance Agency has helped countless wedding planners in the Midwest steer the complexities of liability insurance for wedding planners. Our team has seen how the right coverage transforms a vulnerable business into a protected, professional operation that clients trust.
Liability insurance for wedding planners vocab explained:
- general liability insurance costs
- general liability insurance for events
- general liability insurance reviews
Why Insurance is a Must-Have for Your Wedding Planning Business
Imagine the perfect wedding day: every detail carefully planned, every vendor coordinated, every guest beaming. Now, imagine a tiny, unforeseen mishap that threatens to solve it all. This is where liability insurance for wedding planners steps in, acting as your business’s safety net.
Wedding planners, by the very nature of their work, face a myriad of common risks. You’re orchestrating complex events, often in unfamiliar venues, with numerous third-party vendors and hundreds of guests. This environment, while exciting, is ripe for potential accidents. A client could trip on a rug in your office and get injured, or a guest might slip on a dance floor you just had wiped down. These are not just theoretical concerns; slips and falls are a leading cause of claims, and general liability insurance could cover medical expenses in such scenarios.
Beyond physical accidents, you also face the risk of lawsuits stemming from client dissatisfaction or perceived negligence. Even if you’ve done everything right, a client might claim an event was substandard and sue. Without proper protection, legal fees alone could cost upwards of $50,000, not to mention potential damages.
Furthermore, wedding venues almost universally require event planners to carry specific insurance coverage. This isn’t just a suggestion; it’s a contractual and often legal requirement. Providing a Certificate of Insurance (COI) not only grants you access to venues but also showcases your professionalism and commitment to responsible business practices. It signals to both venues and clients that you’re prepared for the unexpected, offering them peace of mind.
At Copeland Insurance Agency, we understand the unique challenges faced by wedding planners in Kansas, Arizona, and Texas. We’re here to help you steer these risks and ensure your business is fully protected. Learn more about how we can help with your small business liability insurance.
The High Stakes of Wedding Day Risks
The “big day” is truly big, not just in joy but in potential liabilities. Let’s explore some high-stakes scenarios:
- Vendor No-Shows: You’ve booked the perfect band, but they don’t show up. The couple sues you, the planner, even though it was the venue’s responsibility to provide the band. While frustrating, professional liability insurance can help protect you from such claims.
- Guest Accidents: A child trips over a cord during setup and injures themselves, or a guest falls and breaks an ankle due to an unsecured cable. These bodily injury claims can result in significant medical bills and lawsuits.
- Venue Damage: While setting up, a team member accidentally scratches the venue’s wood floor, or a confetti cannon leaves stains on the dance floor. Your business could be liable for repair or cleaning costs. We’ve even heard of a candle setting fire to curtains or a glass of wine splashing on valuable art.
- Reputational Damage: Even if a claim is unfounded, the process of defending against it can be time-consuming and damaging to your reputation. Having insurance demonstrates your foresight and commitment to your clients.
- Financial Loss: Legal defense costs, settlements, and judgments can quickly deplete your business’s financial assets. Insurance protects you from these devastating out-of-pocket expenses.

These aren’t just “what ifs”; they are real-world scenarios that can and do happen. Protecting your business from these high stakes is not just smart, it’s essential for long-term success.
Meeting Venue and Legal Requirements
A key component of your insurance portfolio will be the Certificate of Insurance (COI). This document serves as official proof of your insurance coverage. Most wedding venues will require a COI from you before you can begin planning or setting up an event. They might also require to be listed as an “Additional Insured” on your policy. This means that they also receive coverage under your policy for claims arising from your operations at their venue. It’s a common contractual obligation that protects all parties involved.
Meeting these requirements isn’t just about compliance; it’s about establishing trust and professionalism. When you can readily provide a COI and add venues as additional insureds, it streamlines the planning process and assures your partners that you operate a legitimate and responsible business. We ensure our clients have instant access to their COIs, making this process seamless.
State regulations also play a role. While specific insurance requirements for wedding planners can vary by state, general business insurance, like workers’ compensation if you have employees, is often legally mandated. We understand the specific regulatory landscapes in Kansas, Arizona, and Texas, ensuring your coverage meets all local and state laws.
Understanding Liability Insurance for Wedding Planners: Core Coverages
When we talk about liability insurance for wedding planners, we’re primarily referring to a few core policy types designed to shield your business from financial fallout due to claims or lawsuits. These coverages provide essential financial protection, covering everything from legal defense costs to settlements or judgments. Think of them as the bedrock of your business’s security.
To learn more about comprehensive coverage for your business, explore our business liability insurance.
General Liability: Your First Line of Defense
General Liability (GL) insurance is often the first policy a wedding planner needs. It’s your primary shield against the most common types of third-party claims: bodily injury and property damage.
- Bodily Injury Claims: This covers medical expenses and legal fees if a third party (like a client, guest, or vendor) is injured due to your business operations or on your premises. For example, if a client trips over a rug in your office and gets injured, or a guest trips over an unsecured cable you placed at a wedding reception, general liability could help cover their medical expenses and your legal defense.
- Third-Party Property Damage: If you accidentally cause damage to someone else’s property, GL insurance can cover the repair or replacement costs. This could be anything from scratching a venue’s expensive wood floor while setting up decor to accidentally knocking over an expensive chandelier.
- Medical Payments: Some policies include a medical payments feature that can cover minor medical expenses for injured parties, regardless of who was at fault. This can sometimes prevent a small incident from escalating into a larger lawsuit.
- Personal and Advertising Injury: This less obvious but crucial component covers claims of libel, slander, copyright infringement, or false advertising related to your business activities.
General Liability is a foundational policy that most venues require. It helps protect your business from mishaps and lawsuits. For a broader understanding of what this coverage entails, you can visit our guide on what does general liability insurance cover for contractors?.

Professional Liability (E&O): Protecting Against Costly Mistakes
While General Liability covers physical accidents, what about the “professional” mistakes? That’s where Professional Liability insurance, also known as Errors & Omissions (E&O) insurance, comes in. This coverage is specifically designed for service-based businesses like wedding planning.
E&O protects your business against claims of negligence, errors, or omissions in the professional services you provide. Think of it as a safeguard against claims that you failed to perform your contracted duties or that your advice or actions led to a financial loss for your client.
Consider these scenarios:
- You accidentally send out invitations with the wrong event date, leading to lower attendance and a lawsuit from the client for damages.
- A client claims the event you planned was substandard, perhaps due to a vendor you recommended who underperformed.
- You’re accused of booking the caterer for the wrong date, causing significant disruption and financial loss.
- You mistakenly order the wrong food for a guest with a severe allergy, causing an allergic reaction and requiring medical attention.
In these cases, even if you believe you’re not at fault, the cost of defending yourself in court can be substantial. E&O insurance helps cover legal defense costs, settlements, and judgments arising from such claims. It protects your business when a client claims your service was flawed or caused them harm. We can help you understand the nuances of professional liability insurance for your specific needs.
Common Policy Exclusions to Be Aware Of
While insurance is your business’s trusty sidekick, it’s important to know its limitations. All policies have exclusions, which are specific situations or types of damage that are not covered. Understanding these helps you identify potential gaps in your coverage.
Common exclusions in general and professional liability policies often include:
- Intentional Acts: If you intentionally cause harm or damage, your policy will not cover it.
- Employee Injuries: General Liability does not cover injuries to your own employees. This falls under Workers’ Compensation insurance.
- Auto Accidents: Accidents involving vehicles used for business purposes are typically excluded from general liability policies and require Commercial Auto insurance.
- Communicable Diseases: Claims arising from the transmission of communicable diseases are often excluded.
- Amusement Devices & Fireworks: Liabilities related to the use of amusement devices (like bounce houses) or fireworks are usually excluded.
- Hazardous Materials: Claims involving asbestos, lead, or nuclear energy are typically not covered.
- Operations Outside of the U.S.: Coverage usually applies only to operations within the United States and its territories.
- Outside Concessionaires and Vendors: While your policy covers your operations, it typically won’t cover claims arising directly from the negligence of other independent vendors or concessionaires. This is why venues often require all vendors to have their own insurance.
- Violation of Statutes Governing Electronic Communications: Claims related to violations of privacy laws concerning electronic communications may be excluded.
- Cyber Attacks: While you collect client data, general liability does not cover data breaches or cyber incidents. This requires a dedicated Cyber Liability policy.
Being aware of these exclusions allows you to seek additional, specialized coverages where necessary, ensuring comprehensive protection for your wedding planning business.
Expanding Your Coverage: Other Essential Policies
While liability insurance for wedding planners covers the foundation of your protection, running a successful wedding planning business requires thinking beyond just liability coverage. Your business has unique needs that extend to your physical assets, employees, vehicles, and the digital information you handle every day.
Think of it this way: general and professional liability are like having a great security system for your home, but you still need insurance for your belongings, your car, and protection against identity theft. The same principle applies to your wedding planning business.
At Copeland Insurance Agency, we’ve seen how the right combination of coverages creates a safety net that lets you focus on creating magical moments instead of worrying about “what if” scenarios. Let’s explore the additional protections that can make your business truly bulletproof. You can learn more about our comprehensive business insurance solutions.
Business Owner’s Policy (BOP)
If you’re looking for smart, cost-effective coverage, a Business Owner’s Policy (BOP) might be your new best friend. This clever insurance package combines two essential coverages into one convenient policy that often costs less than buying them separately.
General liability protection handles those third-party claims we discussed earlier, while commercial property insurance protects all the physical stuff that makes your business run. We’re talking about your office space (whether you own or rent), your computer equipment, that expensive sound system you use for events, your carefully curated collection of sample centerpieces, and even your office furniture.
Picture this: a pipe bursts in your office building over the weekend, soaking your computers, client files, and sample materials. Or imagine a break-in where thieves make off with your laptop containing months of client work. Commercial property coverage steps in to replace or repair these essential business assets.
But here’s where it gets even better – many BOPs also include business income coverage. If property damage forces you to close your office temporarily, this coverage helps replace the income you lose while getting back on your feet. It’s like having a financial cushion that keeps your business afloat during the recovery period.
Commercial Auto and Workers’ Compensation
As your wedding planning business grows, you’ll likely find yourself on the road more often and possibly bringing on help for busy seasons. That’s when these two coverages become absolutely essential.
Commercial auto insurance protects you when personal auto insurance won’t. If you’re driving to meet a client, transporting decorations to a venue, or even just grabbing supplies for an event, you’re using your vehicle for business purposes. Most personal auto policies have exclusions for business use, leaving you vulnerable if an accident happens during these activities.
This coverage extends beyond just your own vehicle too. It includes hired and non-owned auto coverage, which protects you if you rent a van to transport wedding supplies or if an employee uses their personal car for a business errand and gets into an accident.
Workers’ compensation becomes crucial the moment you hire your first employee, even if they’re just helping part-time during wedding season. Most states legally require this coverage, and for good reason. Wedding setup involves physical work – lifting, carrying, decorating – and accidents can happen.
If an employee slips while setting up a ceremony arch or strains their back moving heavy equipment, workers’ compensation covers their medical expenses and lost wages. More importantly, it protects your business from potential lawsuits. Without this coverage, an injured employee could sue your business directly, putting your personal assets at risk.
Cyber Liability in the Digital Age
Here’s a sobering thought: as a wedding planner, you’re essentially running a data collection business. Client names, addresses, phone numbers, email addresses, credit card information, guest lists, vendor contacts – your computer systems are treasure troves of sensitive information that cybercriminals love to target.
Data breaches can happen to any business, regardless of size. Maybe it’s a sophisticated hacking attack, or perhaps a laptop gets stolen from your car with unencrypted client files. Either way, you’re facing a expensive nightmare of notification requirements, credit monitoring services for affected clients, legal fees, and potential lawsuits.
Ransomware attacks are becoming increasingly common, where criminals lock down your computer systems and demand payment for the key to open up them. Imagine losing access to all your client files, vendor contacts, and planning software right before wedding season kicks into high gear.
The financial impact is staggering. According to recent industry data, cyber incident claims averaged nearly $169,000 in 2023. But cyber liability insurance doesn’t just write you a check – it provides access to expert breach response teams who guide you through the crisis step by step, from initial investigation to client notification to reputation management.
In our digital world, cyber liability insurance isn’t just smart business – it’s essential for maintaining client trust and protecting your reputation. Learn more about how cyber liability insurance can safeguard your wedding planning business.
The Practical Guide to Getting Insured
Getting the right liability insurance for wedding planners doesn’t have to feel overwhelming. At Copeland Insurance Agency, we’ve streamlined the process to make protecting your business as simple as planning your next event. Whether you’re coordinating intimate ceremonies in Manhattan, KS, or grand celebrations in Scottsdale, AZ, we’re here to guide you every step of the way. For comprehensive coverage options custom to your industry, explore our insurance for event planners.
How Much Does Liability Insurance for Wedding Planners Cost?
The honest answer? It depends on your unique business situation. Just like every wedding you plan has its own personality and requirements, your insurance premium reflects the specific characteristics of your operation.
Business size plays a major role in determining your costs. A solo planner working from home will typically pay less than an established agency with multiple coordinators and a showroom. Your location matters too – premiums can vary between our service areas in Kansas, Arizona, and Texas based on local risk factors and state regulations.
The number of events you handle annually is perhaps the biggest cost factor. If you’re planning dozens of weddings each year, an annual policy becomes incredibly cost-effective – sometimes as low as $8.25 per month. Compare that to per-event coverage, which might run $50-75 per wedding, and the savings add up quickly.
Your services offered also influence pricing. A planner who handles full-service coordination including setup and breakdown faces different risks than someone focused purely on vendor coordination and timeline management. Similarly, your claims history significantly impacts your premium – a clean record keeps costs down, while past claims can increase your rates.
Coverage limits and deductibles give you control over your premium. Choosing higher limits (like $2 million instead of $1 million) increases your cost but provides better protection. Selecting a higher deductible – the amount you pay before insurance kicks in – can lower your monthly premium.
Most wedding planners can expect to pay between $300 and $1,000 annually for comprehensive general liability coverage, though your specific quote will reflect your business’s unique risk profile.
Getting a Quote and Proof of Insurance
Starting your insurance journey is straightforward. We’ll ask for some basic information about your business to ensure we provide the most accurate quote possible. This includes details about your business location (which helps us steer state-specific requirements), number of employees, and gross annual sales to gauge your business size and exposure.
We’ll also want to know about your payroll size for workers’ compensation considerations, details about your business property and equipment, and the types of weddings you typically plan. Do you specialize in intimate backyard gatherings or elaborate ballroom affairs? These details help us tailor your coverage perfectly.
Once you’ve secured your policy, getting your Certificate of Insurance (COI) is immediate. This official proof of coverage is what venues require before allowing you access to their facilities. With modern insurance platforms, you can generate and download your COI instantly, then email it directly to venues or clients who need it.

Adding venues as “Additional Insureds” is equally simple – a few clicks online and they’re covered under your policy for claims arising from your work at their location. This seamless process eliminates the back-and-forth that used to slow down venue bookings.
Annual Policy vs. Per-Event Coverage
Choosing between annual coverage and per-event insurance is like deciding between a season pass and individual tickets – it all comes down to how often you’ll use it.
| Feature | Annual Policy | Per-Event Coverage |
|---|---|---|
| Cost | Often more cost-effective for frequent planners | Can be more expensive per event if you do many |
| Number of Events | Covers unlimited events within the policy term | Covers a single event or a defined short period |
| Commitment | Provides continuous coverage for 12 months | Flexible, on-demand, ideal for occasional planners |
| Premium Example | As low as $8.25 per month | Starts around $50 per event |
| Proof of Insurance | One policy, easy to generate COIs for all events | New COI needed for each event |
| Best For | Full-time planners, agencies with consistent bookings | Part-time planners, single projects, new businesses |
Annual policies shine when you’re planning multiple events throughout the year. The continuous coverage means you’re always protected, whether you’re meeting with vendors, scouting venues, or coordinating events. Plus, the administrative simplicity can’t be beat – one policy covers everything, making COI generation effortless.
Per-event coverage offers flexibility that appeals to part-time planners or those just starting their businesses. Maybe you’re testing the waters with wedding planning while maintaining another career, or perhaps you only take on a few select events each year. In these cases, paying only for the coverage you need makes financial sense.
The math is straightforward: if you’re planning more than six to eight events annually, an annual policy typically becomes more economical. But beyond the numbers, annual coverage provides peace of mind and professional credibility that clients and venues recognize and appreciate.
Conclusion
Your journey as a wedding planner is built on turning dreams into reality, creating those perfect moments that couples will treasure forever. At Copeland Insurance Agency, we share that same dedication – but our focus is protecting the business that makes those magical moments possible.
Liability insurance for wedding planners isn’t just another business expense or paperwork requirement. It’s your professional foundation, the safety net that lets you pour your heart into every event without worrying about what could go wrong. When you’re protected by comprehensive coverage, you can focus entirely on what you do best: crafting unforgettable celebrations.
Think about it this way: every successful wedding planner knows that backup plans are essential. You have contingency vendors, alternative timeline options, and emergency kits packed with everything from safety pins to stain removers. Insurance is simply the ultimate backup plan for your business itself.
The peace of mind that comes with proper coverage extends far beyond your own comfort. When venues see your Certificate of Insurance, they know you’re a serious professional. When clients learn you’re fully insured, they trust you with their most important day. This protection builds credibility that sets you apart in a competitive industry.
We’ve spent years understanding the unique challenges facing wedding planners across Kansas, Arizona, and Texas. From the intimate barn weddings in rural Kansas to the elaborate resort celebrations in Arizona, we know the risks you face and the coverage you need. Our team is here to make insurance simple, affordable, and custom to your specific business.
Don’t let an uninsured risk threaten everything you’ve worked to build. Your passion deserves protection, your clients deserve confidence, and your business deserves to thrive. Let us help you create that solid foundation so you can keep creating those once-in-a-lifetime moments.