

Liability Insurance for Realtors: Protect Your Practice 2025
Why Real Estate Professionals Face Serious Financial Risks Without Proper Coverage
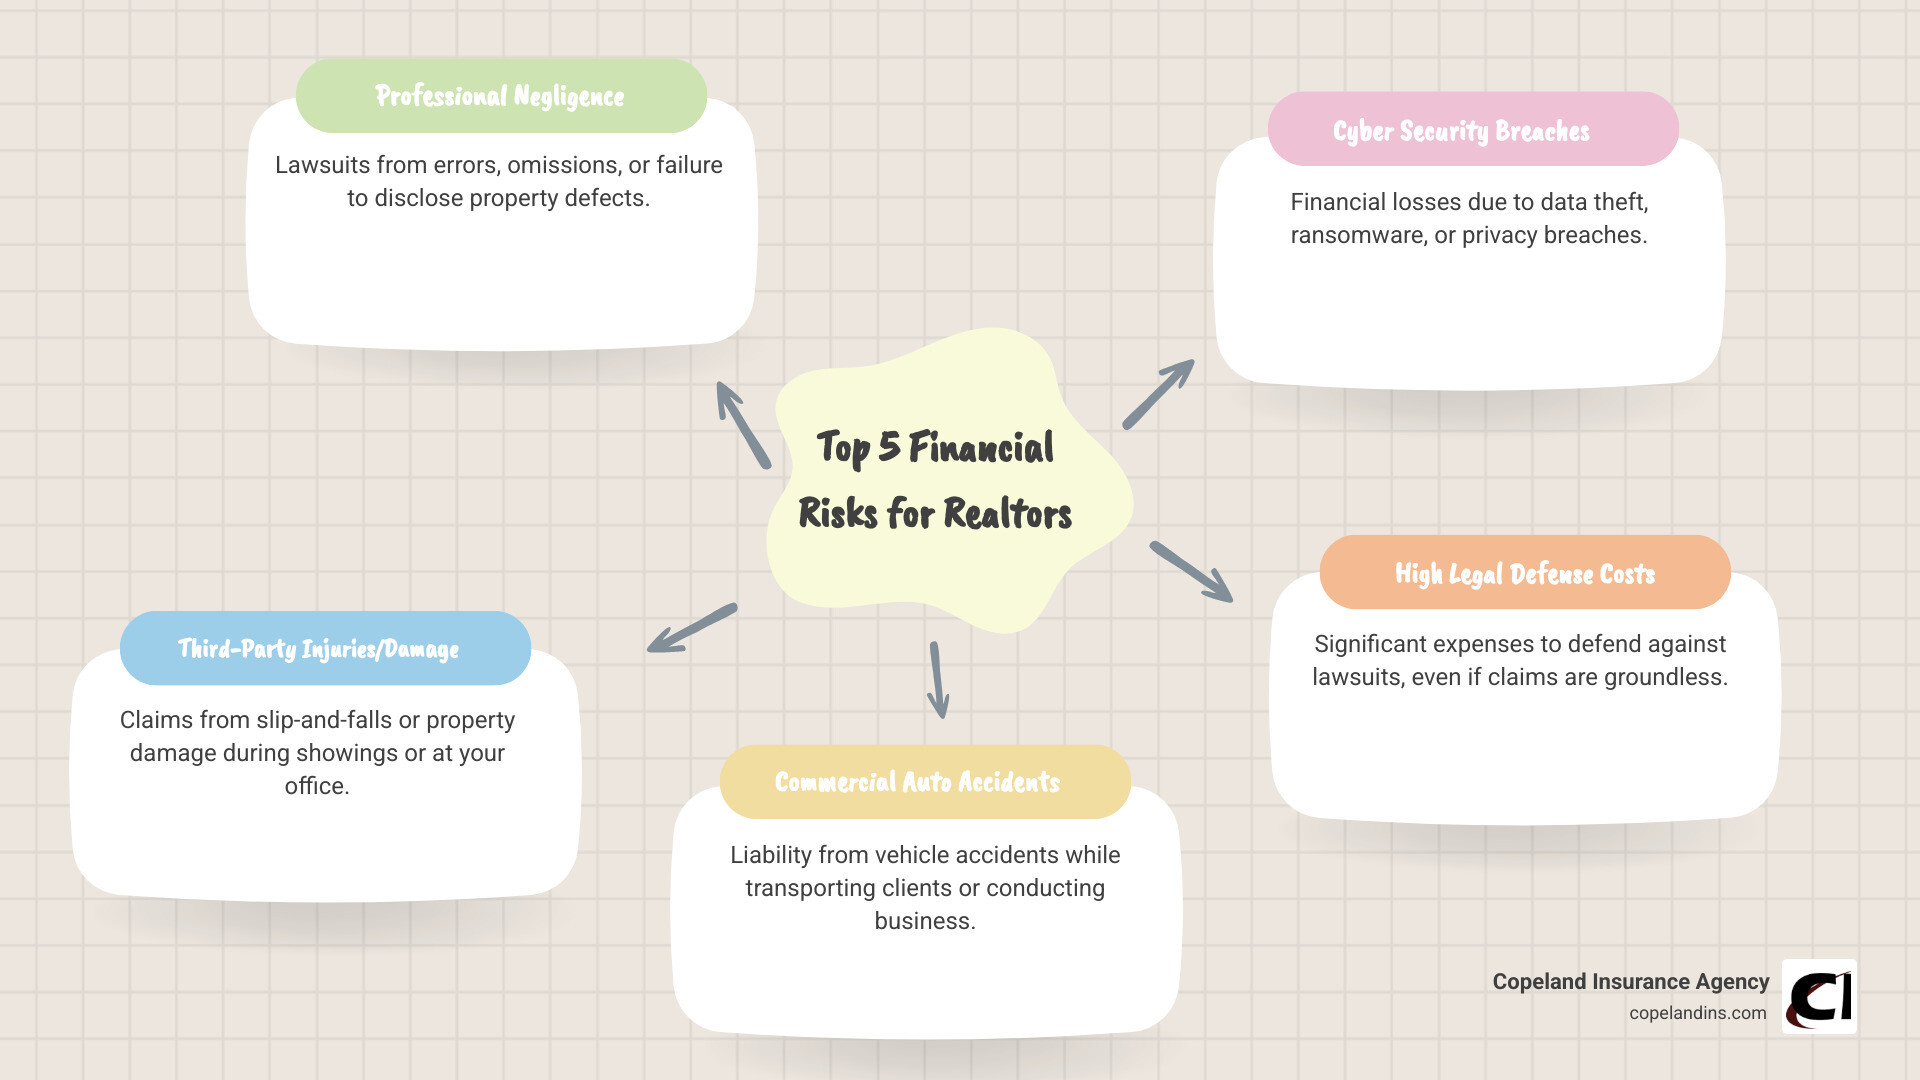
Liability insurance for realtors protects real estate professionals from costly lawsuits and financial losses that can arise from professional mistakes, client injuries, or property damage during business operations.
Key Coverage Types for Real Estate Agents:
- Errors & Omissions (E&O) Insurance – Covers professional mistakes, negligence, and failure to disclose property defects.
- General Liability Insurance – Protects against client injuries and property damage at your office or during showings.
- Commercial Auto Insurance – Covers accidents while transporting clients.
- Cyber Liability Insurance – Protects against data breaches and cyber attacks.
Real estate is an inherently risky business. As one industry expert notes: “Working as a real estate agent or broker comes with an inherent amount of legal risk.” Every transaction involves significant money, emotions, and complex legal requirements, creating multiple opportunities for things to go wrong.
Consider these realities:
- Malpractice lawsuits against real estate agents are common and can cost hundreds of thousands of dollars.
- A single undisclosed property defect can lead to devastating financial consequences.
- Even groundless accusations require an expensive legal defense.
The good news is that the right insurance can protect your business and personal assets. Most real estate businesses pay a median of just $30 per month for general liability insurance, while E&O coverage ranges from several hundred to several thousand dollars annually—a small price for peace of mind.
With over two decades of experience helping real estate professionals secure comprehensive liability insurance for realtors, our team has seen how proper coverage protects agents from career-ending financial disasters. At Copeland Insurance Agency, we specialize in crafting custom insurance solutions that address the unique risks facing today’s real estate professionals.
Basic liability insurance for realtors vocab:
- general liability insurance costs
- liability insurance for home inspectors
- liability insurance for lawyers
The Core Policy: Errors & Omissions (E&O) Insurance Explained

When helping clients with major financial decisions like buying or selling a home, mistakes can happen despite the best intentions. Errors & Omissions (E&O) insurance is a professional safety net that protects you when clients claim you made an error, gave bad advice, or failed to disclose something important. It covers claims of negligence, misrepresentation, inaccurate advice, or failure in your fiduciary duty. Unlike general liability, which covers physical harm, E&O specifically protects against claims related to your professional services.
At Copeland Insurance Agency, we’ve seen how quickly a simple misunderstanding can turn into a costly lawsuit. That’s why we specialize in comprehensive Professional Liability Insurance and Errors And Omissions Liability Insurance designed for real estate professionals.
What is E&O Insurance and Who Needs It?
Errors & Omissions insurance is professional liability coverage that protects you when clients sue over alleged mistakes in your services. It’s like malpractice insurance for doctors but designed for real estate professionals. Crucially, E&O insurance covers your legal defense even when accusations are groundless, saving you from attorney fees that can quickly reach tens of thousands of dollars.
This protection is essential for everyone in the real estate industry. Real estate agents, brokers (who are often responsible for their agents’ actions), property managers, and appraisers all face significant professional liability risks. Even in states that don’t mandate E&O coverage, it’s considered vital protection. The National Association of REALTORS® emphasizes its importance in their guide on Real Estate E&O Insurance: Understanding the Basics.
Why E&O is Crucial: Common Claim Scenarios
Real estate transactions are complex and emotional, creating a perfect recipe for disputes. Even careful agents can face lawsuits.
Failure to disclose property defects is a top E&O claim. If a buyer finds an issue like basement flooding or foundation problems after closing, they may sue the agent for not disclosing it.
Incorrect property details, such as misrepresenting property access or boundaries, can lead to lawsuits over misrepresentation, even if you relied on information from the seller.
Contract errors and missed deadlines can cause deals to collapse, leading clients to blame their agent for financial losses.
Providing bad advice outside your expertise, such as on tax implications or zoning, can make you liable if a client acts on it and faces problems.
Buyer’s remorse can lead to lawsuits where clients claim you pushed them into a bad deal, requiring a legal defense even if the claim lacks merit.
Common E&O claims against realtors include:
- Undisclosed structural issues or environmental hazards
- Boundary disputes and survey problems
- Zoning restriction misunderstandings
- Financing advice that goes wrong
- Discrimination allegations
- Dual agency conflicts of interest
Quality liability insurance for realtors with proper E&O coverage handles legal defense costs, court fees, and settlements or judgments. It’s the difference between a career-ending disaster and a manageable business expense.
Beyond E&O: General Liability and Other Essential Coverages

While E&O insurance protects against professional mistakes, it doesn’t cover every risk. Physical spaces, client interactions, and digital operations present unique liabilities. For instance, if a client slips and falls in your Salina, KS, office or you accidentally damage a client’s property during a showing, you need General Liability insurance. It covers claims for bodily injury and property damage that are not related to your professional services.
For comprehensive protection, consider exploring our Business Liability Insurance options.
What is General Liability Insurance for a Real Estate Business?
General Liability (GL) insurance is fundamental coverage for any business. It protects you from common “oops” moments, including:
- Bodily injuries: Covers medical and legal costs if a client is injured at your office (e.g., in Overland, KS) or during a showing.
- Property damage: Covers repair or replacement costs if you or an employee damage someone else’s property.
- Advertising injuries: Protects against claims of libel, slander, or copyright infringement in your marketing.
With a median cost of just $30 per month, GL is an affordable and essential part of your risk management strategy. To secure this vital protection, check out our General Liability Insurance Companies For Small Business offerings.
Comparing E&O and General Liability Insurance for Realtors
Understanding the difference between E&O and GL is key. E&O covers your professional services, while GL covers the physical risks around your business operations.
| Coverage Type | Protects Against | Example Claim |
|---|---|---|
| Errors & Omissions (E&O) / Professional Liability | Claims of negligence, mistakes, or failure to perform professional duties. | A client sues you for failing to disclose a known structural defect. |
| General Liability (GL) | Claims for bodily injury, property damage, or advertising injury. | A client slips and falls in your office, or you break a vase during a showing. |
As you can see, both are critical pieces of your overall liability insurance for realtors puzzle.
Other Recommended Policies
A truly comprehensive plan includes other key policies:
-
Business Owner’s Policy (BOP): Ideal for many real estate agencies in places like Junction City, KS, a BOP bundles General Liability and Commercial Property insurance into one affordable policy.
-
Commercial Property Insurance: If you own or lease an office in a place like Topeka, KS, this policy is vital. It protects your physical assets (building, equipment) from fire, theft, and other covered events. Learn more about our Commercial Property Insurance options.
-
Commercial Auto Insurance: Your personal auto policy may not cover accidents while transporting clients. A Commercial Auto policy is crucial for agents on the go in areas like Abilene, KS.
-
Cyber Liability Insurance: Real estate professionals handle sensitive client data. This insurance helps cover costs from data breaches, such as notification, legal fees, and fines.
-
Commercial Umbrella Insurance: This provides an extra layer of liability protection above your other policies. If a major claim exceeds your primary limits, this policy kicks in, preventing a catastrophic loss. Explore our Commercial Umbrella Insurance options.
By considering this comprehensive suite of insurance policies, you’re not just buying protection; you’re investing in the long-term stability and success of your real estate business.
Cost and State Requirements for Liability Insurance for Realtors

Understanding the cost of liability insurance for realtors and state requirements is key. While premiums vary, the cost is a small investment compared to the potential expense of a lawsuit. For a general overview, visit our page on Understanding Your Small Business Liability Insurance Cost.
Factors That Influence Your Insurance Premiums
Insurance premiums are calculated based on several factors:
- Location: Costs vary geographically. Operating in urban areas of Arizona or Texas may lead to higher premiums than in rural Kansas due to different litigation rates.
- Brokerage Size and Structure: The number of agents, annual revenue, and business structure (sole proprietorship, LLC, etc.) all impact your premium.
- Annual Revenue: Higher revenue often correlates with more transactions and greater exposure, influencing cost.
- Claims History: A clean claims history can significantly reduce your premiums, while past claims will likely increase them.
- Policy Limits and Deductibles: Higher coverage limits and lower deductibles result in higher premiums. It’s a balance between protection and affordability.
- Type of Real Estate: Handling residential sales, commercial transactions, or property management carries different risk profiles and affects your premium.
- Risk Management Practices: Proactive risk management, such as clear office policies and agent training, can signal lower risk and potentially lead to discounts.
- Bundling Policies: Bundling policies like E&O and General Liability can often save you money.
While the median cost for general liability is around $30 per month, E&O costs can range from several hundred to several thousand dollars annually. We work with multiple carriers to find competitive rates for your needs in states like Arizona, Texas, and Kansas.
State-Specific E&O Requirements
E&O insurance requirements vary by state. Some states mandate it for licensing.
States known to have mandatory E&O programs include:
- Nebraska
- North Dakota
- New Mexico
- Rhode Island
- Tennessee
In these states, agents must often join a group policy or show proof of individual coverage meeting state minimums. For example, the Nebraska Real Estate Commission provides an Errors & Omissions Insurance Fact Sheet outlining their rules.
Even in states like Kansas, Arizona, or Texas, where E&O may not be state-mandated, many brokerages require it. It’s essential to:
- Verify local laws: Check with your state’s real estate commission for current requirements.
- Understand brokerage rules: Comply with your brokerage’s internal insurance mandates.
- Follow best practices: Regardless of requirements, carrying E&O is a professional best practice that protects your assets.
We can help you steer these state-specific nuances, whether you’re in Marysville, KS, or a larger market.
Frequently Asked Questions about Realtor Liability Insurance
We understand that liability insurance for realtors can be complex. Here are answers to the most common questions we hear from real estate professionals.
Does my broker’s E&O policy provide enough coverage for me as an individual agent?
Not always. Relying solely on your broker’s policy can be risky. A broker’s policy has shared limits, meaning a large claim against the brokerage or claims from other agents can exhaust the coverage, leaving you exposed. The policy may also have exclusions for certain services you provide.
Furthermore, if you switch brokerages or the policy lapses, you could lose coverage for past work. For these reasons, many experts, including the National Association of REALTORS®, recommend that individual agents carry their own E&O policy. It provides you with dedicated limits and continuous protection throughout your career.
What is the difference between a “claims-made” and an “occurrence” policy?
Understanding this distinction is essential for E&O coverage.
A claims-made policy, the most common for E&O, covers claims made and reported during the policy period. To be covered, your policy must be active both when the error occurred and when the claim is filed. If you cancel your policy, you lose coverage for past incidents. That’s why Extended Reporting Period (ERP) or “tail coverage” is vital; it extends the time you can report claims after your policy ends.
An occurrence policy covers any incident that happens during the policy period, regardless of when the claim is filed. These are rare for professional liability but common for general liability. Because most E&O policies are claims-made, maintaining continuous coverage is critical.
How much liability coverage do I actually need?
The right amount of coverage depends on your unique situation. Start by checking any state minimums, but don’t assume that’s enough. Consider these factors:
- Transaction values: Agents selling high-value homes in areas like Scottsdale, Arizona, need higher limits than those handling starter homes in small-town Kansas.
- Volume of business: More transactions mean more exposure to potential claims.
- Business structure and risk tolerance: Your needs will differ if you’re an independent agent versus part of a large brokerage.
Common liability policy limits range from $500,000 to $1 million per occurrence. At Copeland Insurance Agency, we can help you analyze your practice and find the right balance between comprehensive protection and affordable premiums. The cost of adequate coverage is always less than the cost of being underinsured when a claim hits.
Conclusion: Partner with an Expert to Protect Your Livelihood
In the , high-stakes world of real estate, having the right liability insurance for realtors isn’t just a good idea – it’s an absolute must. We’ve taken a close look at how Errors & Omissions (E&O) insurance acts as your personal shield against those tricky claims of professional mistakes, misrepresentation, or advice gone wrong. It truly protects your hard-earned reputation and financial security in every real estate transaction.
But it’s not just about professional advice! We also saw how crucial General Liability insurance is for those everyday “oops” moments, like a client taking an unexpected tumble in your office or accidental damage during a showing. These two policies, E&O and GL, are the cornerstones of your protection.
For truly comprehensive coverage, remember those other important policies we talked about: Commercial Auto for your travels, Cyber Liability to guard your sensitive data, and Commercial Umbrella for that extra layer of peace of mind. When you combine them, you build a strong, multi-layered defense for your entire business. Think of it as a small, smart investment today that saves you from potentially massive costs and worries tomorrow.
At Copeland Insurance Agency, we truly believe that getting the right insurance is the smartest move you can make for proactive Risk Management. With over two decades of experience and a warm, dedicated customer service approach, we’re here to help you find comprehensive coverage options that fit just right. We understand the unique ins and outs of the real estate world, whether you’re working in Kansas, Arizona, or Texas. Our goal is simple: to help you protect your assets and secure your business’s future.
Don’t leave your livelihood to chance. Partner with us, your trusted insurance experts, and gain the peace of mind you need to focus on what you do best – helping clients find their perfect properties and achieve their real estate dreams.
Ready to take that essential step? Get a quote for your business liability insurance needs today and safeguard your real estate practice!