

Home Insurance Junction City KS 2025: Secure Peace
Why Junction City Homeowners Need Proper Insurance Protection
Home insurance junction city ks is essential for protecting your most valuable investment. For homeowners near Fort Riley or those who have lived in the Flint Hills community for years, the right coverage protects you from unexpected events like severe weather, theft, or liability claims, ensuring financial security for your family.
Quick Answer for Junction City Home Insurance Seekers:
- Average Cost: Approximately $1,500 per year in Junction City, KS
- Top Providers: A mix of national carriers and local independent agencies
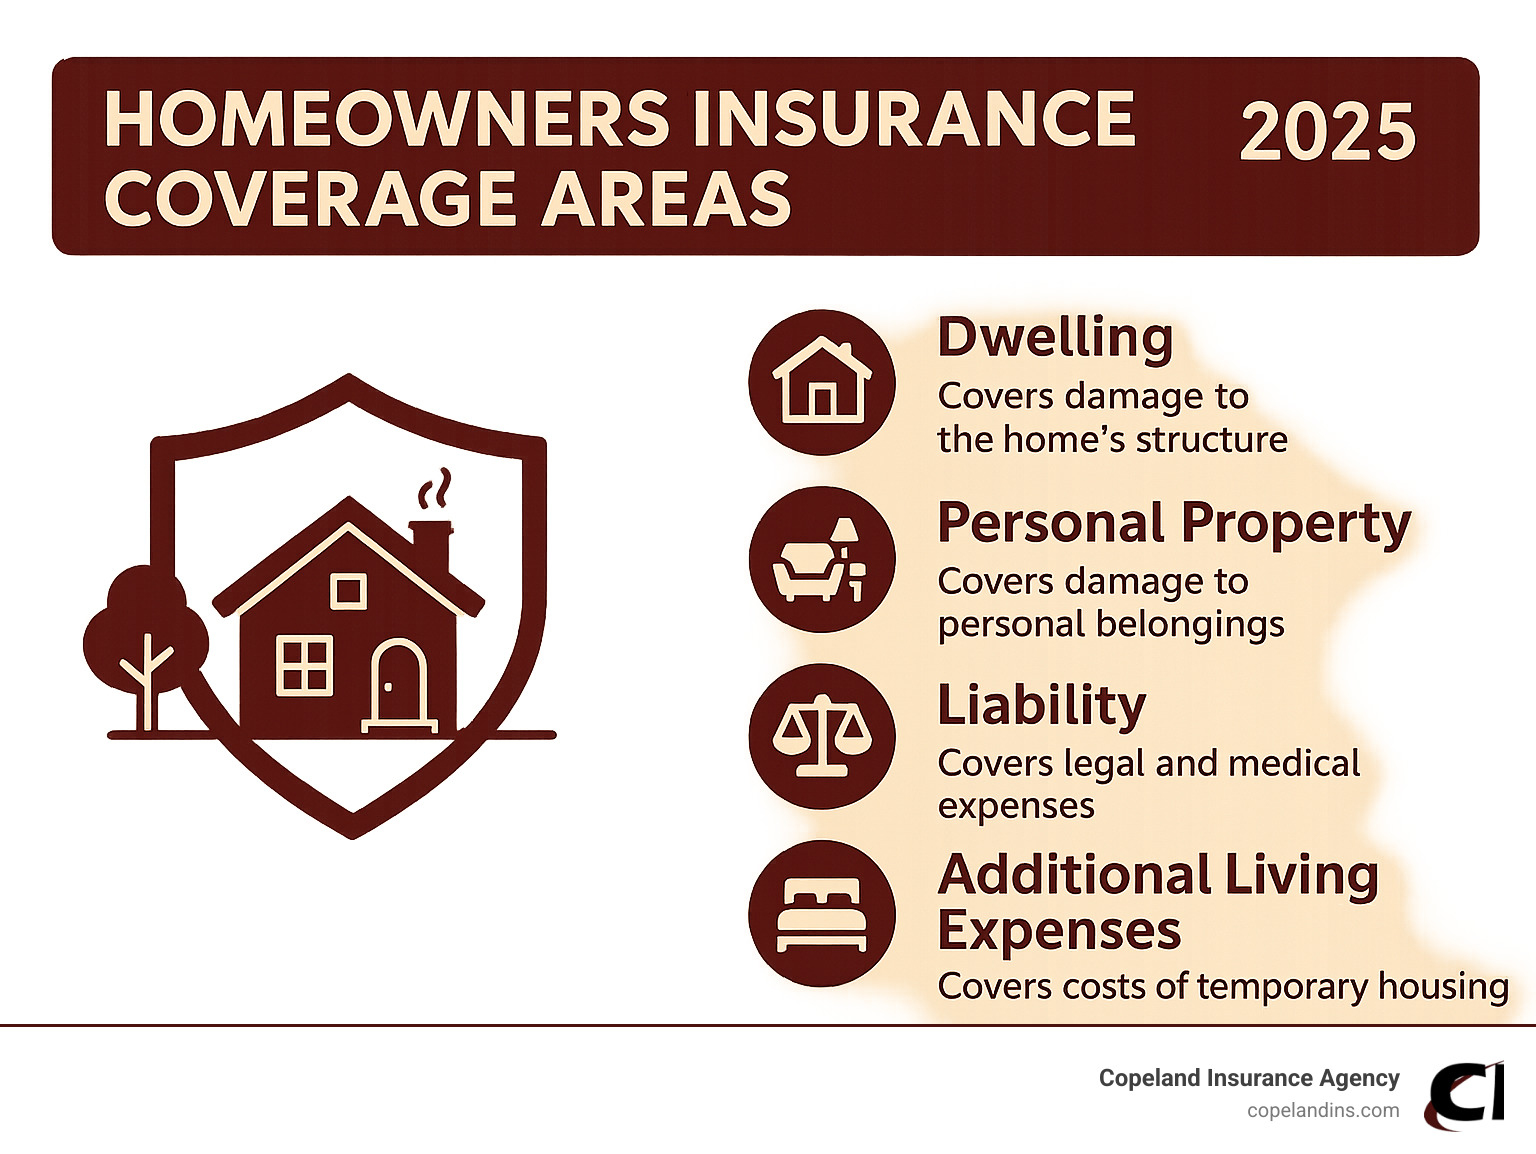
- Key Coverage Areas: Dwelling, personal property, liability, additional living expenses
- Local Factors: Kansas weather risks, home age/condition, proximity to fire protection
- Discounts Available: Multi-policy bundles, security systems, claims-free history
Your home faces unique risks in Kansas, from severe thunderstorms and hail to tornadoes that can cause significant damage. The right insurance policy doesn’t just protect your house; it safeguards your financial future and gives you peace of mind knowing you can rebuild and recover from life’s unexpected challenges.
At Copeland Insurance Agency, our team of Certified Professional Insurance Agents has spent over two decades helping Junction City families secure comprehensive home insurance junction city ks coverage. Our experience has shown us that every home and family has unique protection needs that require personalized attention and expert guidance.
Understanding Your Home Insurance Coverage
Understanding your home insurance junction city ks policy is key to ensuring you have the right protection. A homeowners policy is a multi-layered safety net designed to protect you from various financial risks, and each layer serves a distinct and vital purpose for your financial well-being.
Dwelling Coverage forms the foundation, protecting your home’s physical structure. This includes not just the foundation, walls, and roof, but also attached structures like a garage, deck, or porch. It helps repair or rebuild your home after damage from events like Kansas storms. The coverage amount is based on the current cost to reconstruct your house, not its market value. This distinction is critical because market value includes the cost of land, which is not at risk from perils like fire or wind, ensuring your coverage is sufficient to actually rebuild.
Personal Property coverage protects your belongings, such as furniture, electronics, and clothing, whether they are inside your home or elsewhere. This protection applies even when your items are away from home, like a laptop stolen from a hotel room or sports equipment taken from your car. It is important to be aware that most policies have sub-limits for high-value items like jewelry, art, and firearms. If the value of your collection exceeds these standard limits, you may need a special endorsement or a separate policy to be fully covered.
Liability Protection is crucial. If a visitor is injured on your property, it covers their medical bills, legal fees, and potential settlements. For example, if a guest slips on an icy walkway and breaks a leg, this coverage would handle the resulting medical expenses and any legal action. A single accident could be financially devastating without this coverage, potentially costing hundreds of thousands of dollars and jeopardizing your assets.
If covered damage makes your home unlivable, Additional Living Expenses (ALE), or Loss of Use coverage, pays for the temporary increase in your costs, such as hotel bills, rent for a temporary apartment, and meals. It can also cover expenses like laundry services or pet boarding if your temporary housing cannot accommodate them. This allows you to maintain your normal standard of living and focus on recovery without the added stress of finding and funding temporary housing.
For homeowners seeking broader protection, Comprehensive Coverage Home Insurance offers improved coverage limits and additional protections.
| Feature | Basic Liability Home Insurance | Comprehensive Home Insurance |
|---|---|---|
| Dwelling Coverage | Limited perils (e.g., fire) | Broad range of perils |
| Personal Property | Limited, often named perils | Broader, open perils |
| Liability Coverage | Standard | Often higher limits |
| Additional Living Exp. | May be limited or not included | Typically included and robust |
| Perils Covered | “Named Perils” (specific list) | “Open Perils” (all, unless excluded) |
| Cost | Generally lower premium | Generally higher premium |
| Peace of Mind | Basic protection | Extensive protection |
Key Coverage in Your Home Insurance Junction City KS Policy
How your home insurance junction city ks policy defines coverage can save you from surprises during a claim. Insurance policies are structured in two main ways.
Named-peril policies only cover what’s specifically listed, such as fire, lightning, or theft. If a peril isn’t listed, it isn’t covered. While these policies cost less, they can leave expensive gaps in your protection, forcing you to pay out-of-pocket for any unlisted event.
Open-peril policies cover everything except what’s specifically excluded in the policy documents. This “all-risk” approach provides much broader protection and greater peace of mind, though it typically comes with higher premiums. Common exclusions include events like floods, earthquakes, and neglect.
Even comprehensive policies have standard exclusions. For Junction City homeowners, the two most important are flood and earthquake damage. Standard policies don’t cover flood damage from overflowing rivers or heavy rain, making separate Flood Insurance essential, especially for properties near the Smoky Hill or Republican Rivers. While less common, earthquakes do occur in Kansas, and Earthquake Insurance covers this excluded peril. Wind and hail damage may also have special deductibles, a nuance we help clients understand to avoid unexpected costs after a storm.
Specialized Policies for Unique Homes
Junction City’s diverse housing requires specialized coverage custom to specific needs.
Historic homes, such as those found in some of Junction City’s older neighborhoods, need policies that cover the high cost of authentic restoration using period-appropriate materials and craftsmanship. Home Insurance for Historic Homes addresses this unique financial challenge.
New construction has its own needs, from builder’s risk insurance during the building phase to policies reflecting modern materials and building codes once completed. Homeowners Insurance for New Construction is designed for this specific lifecycle.
If your home is empty for extended periods, perhaps due to a military deployment or while it is on the market, Vacant Home Insurance protects against the higher risks of vandalism, undetected water damage, and other issues that can arise in an unoccupied property.
Given our proximity to Fort Riley, we often assist military families. Home Insurance for Military Families addresses challenges like frequent relocations, understanding coverage needs during deployments, and ensuring policies can be easily managed from afar.
Every policy balances your premium (what you pay), deductible (your out-of-pocket cost for claims), and coverage limits (the maximum the insurer pays). We help clients find the right balance for their budget and protection needs, ensuring they are neither overpaying for unnecessary coverage nor dangerously underinsured.
What Determines Home Insurance Costs in Junction City, KS?

Ever wonder why your neighbor’s home insurance junction city ks premium is different from yours? While the average is around $1,500 annually in Junction City, this figure is just a starting point. Your actual rate is a highly personalized calculation that depends on several key factors related to your property, your location, and even your personal history.
Living in Kansas means dealing with powerful storms. Insurers factor these Kansas weather risks into every policy, analyzing historical data for your specific ZIP code. This includes the frequency and severity of tornadoes, hailstorms, high winds, and even winter blizzards that can cause roof collapse from heavy snow and ice. A home in an area with a higher frequency of severe weather claims will naturally command a higher premium.
Your home’s age and condition also tell insurers about potential risks. An older home with original, un-updated wiring may pose a higher fire risk than a well-maintained one with modern circuit breakers and GFCI outlets. Similarly, aging plumbing systems, like galvanized pipes prone to corrosion, are more likely to cause water damage claims. Proactive maintenance and system upgrades can directly translate to lower insurance costs.
The construction materials of your home play a big role. In a high-wind area like Geary County, homes built with brick or masonry are often viewed more favorably by insurers than wood-frame houses, as they are more resistant to wind damage. Even your proximity to fire hydrants and the rating of your local fire department can affect your premium, as faster response times reduce the potential for catastrophic fire loss.
To get a personalized estimate based on your home’s unique characteristics, use our Home Insurance Estimate Calculator.
How Your Home’s Features Affect Rates
Your roof condition is one of the most important features insurers examine. A new roof, especially one made with impact-resistant materials, will cost less to insure than an older one nearing the end of its lifespan. The style also matters; a hip roof (sloping on all four sides) often earns lower premiums than a gable roof (with two sloping sides forming a triangle). This is because the aerodynamic design of a hip roof allows high winds to flow over it more easily, reducing the risk of it being lifted off during a severe storm. Learn more at Hip vs Gable Roof Insurance.
Getting a new roof can significantly lower your insurance costs, so always notify your agent. A new roof demonstrates proactive risk management and reduces the likelihood of a costly claim for the insurer. We explain why at Should I tell my agent if I get a new roof?.
Updated electrical and plumbing systems reduce the risk of fire and water damage, which are two of the most common and expensive types of home insurance claims. Insurers reward homeowners who have invested in modern, safer systems, such as replacing old fuse boxes with circuit breakers or upgrading polybutylene pipes.
Protective devices like monitored security systems, smoke detectors, and smart water leak detectors show insurers you’re proactive about preventing losses. A central station-monitored alarm system can deter theft and ensure a faster response to fires, while automatic water shut-off devices can prevent a small leak from becoming a catastrophic flood, often resulting in significant discounts.

Personal Factors That Influence Your Premium
Your claims history impacts your rates. Insurers see a history of frequent claims as an indicator of future risk. Filing several claims in a few years, even for minor incidents, may increase your premium at renewal. Conversely, a long-term claims-free record often qualifies for substantial discounts, as it demonstrates you are a lower-risk policyholder.
Your credit-based insurance score can also be a rating factor in Kansas, as studies show a statistical correlation between credit responsibility and filing fewer claims. This is not the same as your FICO score and does not affect your credit rating, as it is a soft pull. Maintaining a good credit history can positively influence your insurance premiums.
The deductible amount you choose directly affects your premium. A higher deductible means you agree to cover more of the loss yourself, which lowers the insurer’s risk and, in turn, your premium. A lower deductible means a higher premium. The key is finding a deductible you can comfortably afford to pay out-of-pocket on short notice, balancing premium savings with your financial preparedness for a claim.
Insurance rates have been rising nationwide, but we can help you manage costs. Small adjustments, a thorough review of available discounts, and strategic policy structuring can make a significant difference. Learn more about potential relief at As Home Insurance Rates Rise, Some Customers May Get Some Help.
How to Find the Best Home Insurance in Junction City, KS
Finding the best home insurance junction city ks coverage isn’t just about finding the lowest price; it’s about finding the right value. The best policy is one that balances comprehensive coverage that truly protects your assets, fair and competitive pricing, and dependable service from a company that will be there for you during a crisis.
Many homeowners mistakenly assume all policies are the same, but coverage forms, endorsements, and company-specific rules can vary dramatically. The cheapest policy might save you a few dollars upfront but could leave you financially vulnerable with high deductibles, insufficient coverage limits, or critical exclusions that only become apparent after a disaster strikes.
When evaluating providers, consider several factors beyond the premium. Company reputation indicates a track record of paying claims fairly and promptly. Look at ratings from independent agencies like A.M. Best for financial health and J.D. Power for customer satisfaction. Customer service is vital during the stressful claims process. Financial stability ensures the company has the resources to pay claims, even after a major catastrophe impacts a large number of policyholders.
If you’re working with an agent, you can check an agent’s background on FINRA’s BrokerCheck to verify their credentials and professional history.
How to Compare Home Insurance Junction City KS Rates
Comparing home insurance junction city ks rates can be straightforward if you approach it systematically.
Start by gathering your home information, including its year built, square footage, construction materials (roof and siding), dates of any updates to the roof, electrical, and plumbing systems, and a list of safety features. Having this information ready ensures you receive accurate, apples-to-apples quotes.
Online quote tools are helpful for initial research. Our Home Insurance Online Quotes can provide a baseline understanding of potential costs from various carriers. This can help you budget and see how different coverage levels affect the price.
However, the real value comes from speaking with an independent agent. Unlike captive agents who work for a single company and can only offer one set of products, our team at Copeland Insurance Agency partners with multiple top-rated insurers. We do the shopping for you, comparing policies not just on price but on the quality of coverage. This allows us to find unique options, such as carriers that specialize in military families or historic homes, that you might not find on your own. We help you find Competitive Home Insurance Rates without sacrificing essential protection. We recommend reviewing your coverage annually or after any significant life change, as markets and your needs evolve.
Open uping Home Insurance Discounts
Everyone loves saving money on insurance, and there are many opportunities to lower your premium without compromising coverage.
The multi-policy bundle is often the easiest and most significant way to save. Combining your home and auto insurance with the same provider usually results in substantial discounts, often between 10% and 25%, on both policies. You can often achieve even greater savings by bundling additional policies like umbrella or life insurance, and it simplifies your billing and management.
Home safety and mitigation features can lead to real savings on your home insurance junction city ks policy. Monitored security systems, fire alarms, and residential sprinkler systems demonstrate you’re proactive about preventing damage. Newer technologies like smart home leak detectors and automatic water shut-off systems are also increasingly rewarded by insurers. Installing hail-resistant roofing materials can also earn a significant discount in a storm-prone state like Kansas.
Your track record matters. A claims-free history is rewarded by many companies with meaningful discounts that can increase the longer you go without a claim. New homes also often qualify for credits due to modern, safer building codes and systems.
How you pay can also save you money. Insurers may offer small discounts for paying your premium in full for the year, setting up automatic payments from a bank account (EFT), or going paperless. Some companies also provide loyalty discounts for longtime customers or for affiliations with certain groups or employers.
At Copeland Insurance Agency, we are experts at identifying all available discounts to maximize your savings. For a full breakdown, explore our guide on Best Home Insurance Discounts.
Filing a Home Insurance Claim: A Step-by-Step Guide

Filing a home insurance claim is never planned, but knowing the steps can make a stressful situation manageable. When disaster strikes, from a Kansas hailstorm to a kitchen fire, Copeland Insurance Agency guides our home insurance junction city ks clients through the process.
First, ensure safety first. In case of fire, gas leaks, or dangerous structural damage, evacuate immediately and call 911. Your belongings are replaceable; you are not.
Next, document the damage thoroughly. Take extensive photos and videos of all affected areas and items. Don’t throw anything away until the adjuster has seen it, as this can hurt your claim.
Contact your insurer immediately. Most companies have 24/7 claim reporting. The sooner you report, the faster the process begins. Have your policy number ready. If you need help, call us at Copeland Insurance Agency.
While waiting for an adjuster, make temporary repairs to prevent further damage. Cover a leaking roof with a tarp or board up a broken window. Keep all receipts for materials, as these costs are often reimbursable.
Keep detailed records of every conversation with your insurer, including the date, time, and person you spoke with. This documentation can be invaluable.
When the insurance adjuster inspects your property, be cooperative. Walk them through the damage, show them your photos, and answer questions honestly. They are there to help you get back to normal.
Finally, review the settlement offer carefully. Ensure it covers all documented damage. If you have questions or concerns, contact us. We will help you understand the offer and advocate on your behalf if needed.
Filing a home insurance junction city ks claim doesn’t have to be overwhelming. With proper preparation and support, you can steer the process smoothly. This is why you have insurance – to protect you when the unexpected happens.
Frequently Asked Questions about Home Insurance
When it comes to home insurance junction city ks, we hear many of the same questions from homeowners. Let’s address the most common concerns we receive at Copeland Insurance Agency.
What is the difference between replacement cost and actual cash value?
This is a critical distinction that can mean thousands of dollars during a claim.
Replacement cost coverage pays to replace your damaged items with new ones of similar quality. If a fire destroys your five-year-old refrigerator, this coverage pays for a brand new one, without factoring in depreciation.
Actual cash value (ACV) coverage pays for the depreciated value of your items. That same five-year-old refrigerator would be valued at what a used one costs today. While ACV coverage has lower premiums, it can leave you with a significant gap between the payout and the cost of a new item.
Most families find replacement cost coverage provides the financial security needed to fully recover. We help clients choose the option that best fits their budget and needs.
Does homeowners insurance cover damage from tornadoes and hail in Kansas?
Yes, a standard homeowners policy covers tornado and hail damage. However, it’s important to understand wind and hail deductibles.
This deductible is often separate and higher than your standard deductible. It’s typically calculated as a percentage (e.g., 1-5%) of your dwelling coverage, not a flat dollar amount. For a home with $300,000 in dwelling coverage and a 2% deductible, you would pay the first $6,000 of storm damage yourself.
This structure helps insurers manage the high risk of severe weather in our region. We review these specific deductibles with our clients to prevent surprises when a storm hits.
How often should I review my homeowners insurance policy?
Life changes, and your insurance should too. We recommend reviewing your home insurance junction city ks policy at least once a year, and anytime you have a significant life event.
Your home’s value changes with renovations and market fluctuations. A new kitchen or an expensive inheritance might require adjusting your coverage limits to avoid being underinsured.
Major life changes that should trigger a policy review include home improvements, acquiring valuable items (like jewelry or art), or starting a home-based business. Insurance companies also update rates and discounts regularly, so a policy that was competitive last year may not be the best option today.
Regular reviews ensure your coverage matches your current needs and can even uncover new ways to save money.
Secure Your Junction City Home Today
Protecting your home insurance junction city ks investment is about creating a safety net that provides peace of mind. Your home is where you build your life, and it deserves thoughtful, personal protection.
Every Junction City home tells a different story. You might be a military family at Fort Riley, the owner of a historic downtown property, or building a new home in a growing neighborhood.
Whatever your story, a one-size-fits-all policy isn’t enough. Custom coverage makes all the difference. We take the time to understand how you live, what matters most, and what your specific risks are.
Being proactive about protection pays off. With the right coverage, you can focus on your family’s safety during a storm, confident that you are financially protected. This confidence comes from knowing you’ve planned ahead.
At Copeland Insurance Agency, we’ve built our reputation on dedicated customer service and comprehensive coverage options. We believe insurance should be personal, not transactional. We’re here when you’re shopping for a policy, when you need to file a claim, and whenever you have questions.
Ready to give your Junction City home the protection it deserves? Contact Us for a Personalized Quote today. Let’s build a coverage plan that fits your life perfectly.