

Do Farm Trucks Need Insurance? Top 5 Crucial Facts 2025
The Essential Protection Every Farm Truck Needs
Do farm trucks need insurance? Yes, farm trucks typically need insurance, especially when driven on public roads. Most states require at least liability coverage for farm vehicles that travel on public roadways, though specific requirements vary by state.
| Key Insurance Requirements for Farm Trucks |
|---|
| ✅ Liability coverage required for public road use in most states |
| ✅ Farm-only vehicles may have different requirements |
| ✅ Commercial farm operations often need more comprehensive coverage |
| ✅ Even on private property, insurance protects valuable farm assets |
For many farmers, trucks are essential workhorses that keep operations running smoothly. Whether you’re hauling livestock, transporting crops, or moving equipment between fields, these vehicles represent a significant investment in your agricultural business. Without proper insurance coverage, one accident could potentially devastate your livelihood and threaten your farm’s financial stability.
I’m Vonda Copeland, CPIA, CWCU, owner of Copeland Insurance Agency with over two decades of experience helping farmers understand whether do farm trucks need insurance and creating customized coverage solutions that protect their valuable agricultural assets. Let me walk you through everything you need to know about insuring your farm vehicles.
Do farm trucks need insurance vocabulary:
– farm truck insurance
– how much is farm truck insurance
Do Farm Trucks Need Insurance? Understanding Legal Requirements
When it comes to farm trucks, understanding the legal requirements for insurance is crucial for protecting your agricultural business and complying with state laws. The simple answer to “do farm trucks need insurance?” is yes, in most cases—especially when these vehicles will be operated on public roads.
Farm vehicles are subject to specific insurance regulations that can vary significantly depending on your situation. Vehicle type and classification matters – whether your truck is considered a farm vehicle or commercial vehicle affects your requirements. The intended use of your vehicle is equally important – trucks used exclusively on farm property face different regulations than those traveling public roads. State regulations vary considerably from one place to another, and vehicle weight and size often determine how strict the insurance mandates will be.
According to our research at Copeland Insurance Agency, farm trucks used on public roadways need auto insurance coverage similar to other vehicles. This isn’t just about following the law—it’s essential protection for your farm’s financial wellbeing.
As one Kansas farmer told us recently: “I thought my old farm truck would be exempt from insurance requirements since I only used it occasionally on public roads. After speaking with Copeland Insurance, I realized I was taking a huge risk with my farm’s assets. Now I sleep better knowing I’m covered.”
Do Farm Trucks Need Insurance in All States?
The question of whether do farm trucks need insurance across all states has a nuanced answer. While most states require some form of insurance for farm trucks that operate on public roads, the specific requirements can vary significantly.
In states like Kansas, where many of our clients operate, farm vehicles that travel on public roadways must carry liability insurance at minimum. However, the coverage requirements and available exemptions differ based on several factors. State-specific agricultural exemptions exist in many places, offering special provisions for farm vehicles. Each state has different vehicle classification systems that affect how your farm truck is categorized and what insurance it needs. Some states offer exemptions based on distance traveled from the farm, while others consider the frequency of public road use when determining requirements.
For example, in many states, farm trucks with special farm vehicle license plates may have different insurance requirements than those with commercial plates. However, it’s important to note that even if your state has exemptions, operating without insurance still exposes your farm to significant financial risk.
At Copeland Insurance Agency, we stay current on the regulations in all nine states where we’re licensed, including Kansas and Texas, to ensure our farm clients maintain proper coverage while taking advantage of any available agricultural exemptions.
Do Farm Trucks Need Insurance on Public Roads?
When it comes to operating farm trucks on public roads, the answer to “do farm trucks need insurance?” is a definitive yes. This is one area where the law is quite clear across most states.
Any farm vehicle that enters public roadways must have auto insurance that meets at least the minimum state requirements. This typically includes bodily injury liability coverage to protect against injuries you might cause to others, property damage liability coverage to cover damage to other people’s property, and potentially additional coverages depending on your state’s laws.
According to our research, even vehicles primarily used for farming or ranching must follow public road auto insurance requirements when driven off the farm. This remains true regardless of how frequently the vehicle uses public roads—even occasional trips require proper coverage.
As research on farm tractor insurance indicates, while farm equipment may have different requirements than trucks, the principle remains the same: public road use requires insurance coverage.
One of our clients, a multi-generational farm owner near Manhattan, KS, shared: “We use our trucks to transport harvested crops to market several times a year. I learned the hard way that even though these trucks spend 90% of their time on our property, they still need proper insurance for those few trips on public roads. After a minor accident, I was grateful we had the right coverage in place.”
Types of Farm Vehicles That Require Insurance
When you’re running a farm, your vehicles are more than just transportation—they’re the backbone of your operation. From the pickup that hauls feed to the combine that harvests your crops, each vehicle serves a critical purpose. But which ones actually need insurance? It’s a question we hear often at Copeland Insurance Agency.

The simple truth is that most farm vehicles should have some form of insurance protection. Your standard pickup trucks that bounce between fields and occasionally hit the highway definitely need coverage, just like your personal vehicles. Those massive semi-trucks and tractor-trailers hauling your harvest to market? They not only need insurance but often require higher liability limits due to their size and the potential damage they could cause in an accident.
Grain trucks represent a significant investment and carry valuable cargo, making insurance essential for them too. For tractors, ATVs, and self-propelled equipment like combines and sprayers, the requirements can vary depending on how and where you use them. If they ever travel on public roads—even just to cross from one field to another—they typically need insurance coverage.
Did you know that 44% of tractor accidents involve rollovers? With farm equipment often valued between $25,000 and $150,000 (or much more for newer models), going without insurance puts a substantial portion of your farm’s assets at risk.
Even trailers need protection, especially when they’re hitched to a vehicle on public roads. Many farmers don’t realize that trailers can often be added to existing policies for comprehensive protection without breaking the bank.
Insuring Tractors and Farm Equipment
Your tractor might be your most trusted companion on the farm, but it’s also likely one of your biggest investments. Modern tractors and specialized equipment can easily cost well into six figures, making proper insurance not just smart—but essential.
The good news? Specialized tractor insurance is more affordable than many farmers expect. On average, coverage runs about $135 annually—that’s just $11.25 per month to protect equipment worth tens or even hundreds of thousands of dollars. When you look at it that way, the value becomes crystal clear.
One of our clients in Riley, Kansas learned this lesson firsthand. “When our combine was damaged during a sudden hailstorm, having the right insurance policy meant we could repair it quickly and minimize disruption to our harvest schedule. The $200 monthly premium saved us over $45,000 in repair costs.”
When considering insurance for your farm equipment, think about three key areas of protection:
Accident coverage protects you when the unexpected happens—whether it’s a rollover in a steep field or a collision while moving between locations. Theft coverage provides peace of mind in an age when equipment theft is unfortunately common. And repairs coverage helps manage the often substantial costs of fixing damaged equipment.
If you’re still paying off loans on your equipment, your lender will almost certainly require insurance. But even for equipment you own outright, can you really afford to replace or repair it out-of-pocket if something goes wrong? For most farmers, the answer is a clear “no.”
Coverage for Farm Trucks and Grain Haulers
Those hardworking trucks that haul your grain to market or move livestock between pastures deserve special attention when it comes to insurance. They face unique risks and often require coverage custom to agricultural operations.
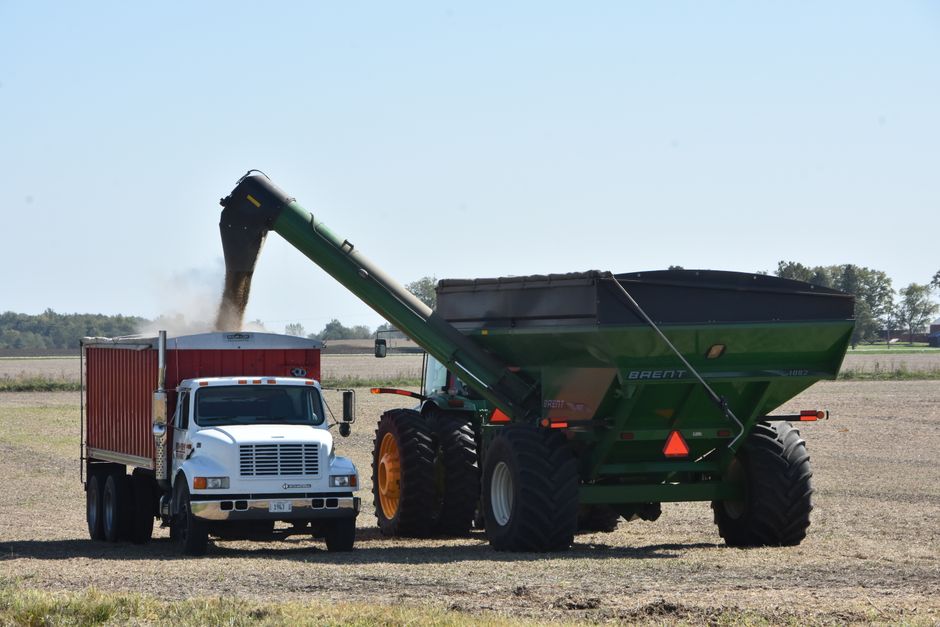
The age and value of your vehicles play a big role in determining appropriate coverage. That 25-year-old semi with an 18-year-old trailer might cost between $950 and $1,050 annually for $1 million in liability coverage. Meanwhile, a 20-year-old grain truck valued around $50,000 might see liability costs ranging from $150 to $400 per year. That’s a small price to pay for protecting vehicles that are essential to your livelihood.
As one grain farmer from Salina, Kansas told us: “During harvest, our grain trucks are constantly on the move between fields and storage facilities. After adding comprehensive coverage to our policy with Copeland Insurance, we were protected when one of our trucks was damaged during a severe thunderstorm. The coverage paid for itself many times over.”
For grain haulers specifically, cargo coverage is often overlooked but incredibly important—it protects the actual value of the crops being transported. Specialized liability coverage addresses risks unique to agricultural hauling, while comprehensive coverage steps in when mother nature strikes or theft occurs.
Seasonal usage patterns matter too. Many farm trucks see intense use during planting and harvest while sitting relatively idle at other times. At Copeland Insurance Agency, we understand these patterns and can help design policies that provide robust protection when you need it without overcharging during slower periods.
Do farm trucks need insurance? Absolutely—but the right coverage should be custom to your specific operation, vehicles, and usage patterns. That’s where our experience with farms across Kansas and beyond makes all the difference.
Types of Insurance Coverage Available for Farm Trucks
Understanding the various types of coverage available for farm trucks is essential for creating a comprehensive insurance policy that protects your agricultural business. Each type of coverage addresses different risks and potential financial exposures.

When farmers ask us “do farm trucks need insurance?“, we explain that not only is some coverage legally required, but a well-designed policy provides crucial protection for your valuable farm assets. At Copeland Insurance Agency, we help farmers understand their options and build policies custom to their specific needs.
The main types of coverage available for your farm trucks include liability (which protects others), collision and comprehensive (which protect your vehicle), and uninsured/underinsured motorist coverage (which protects you from drivers without adequate insurance). Additional options like medical payments, personal injury protection, gap insurance, roadside assistance, rental reimbursement, and non-owned vehicle insurance can provide extra layers of protection.
According to our research, farm truck insurance is often more affordable than standard insurance due to limited usage, lower market value, and potential bundling options. A client from Manhattan, KS recently told us, “I was surprised at how reasonable my farm truck insurance was when bundled with my other farm policies. For the peace of mind it provides during harvest season, it’s worth every penny.”
Liability Coverage for Farm Trucks
Liability coverage is the foundation of any farm truck insurance policy and is typically required by law for vehicles operated on public roads. This coverage protects you financially if you’re responsible for causing damage to others’ property or injuries to other people.
For farm trucks, liability coverage includes two main components:
-
Bodily Injury Liability – Covers medical expenses, lost wages, pain and suffering, and legal defense costs if you injure someone else while operating your farm truck.
-
Property Damage Liability – Pays for damage you cause to other people’s property, including vehicles, buildings, fences, or other structures.
The importance of adequate liability coverage cannot be overstated. As one of our clients from Junction City, KS, found: “When my farm truck slid on ice and damaged another vehicle, my liability coverage handled the other driver’s medical bills and vehicle repairs. Without it, I would have been personally responsible for over $25,000 in damages.”
We typically recommend liability coverage of at least $1,000,000 for farm trucks, especially considering rising medical costs, expensive vehicle repair costs, potential legal defense expenses, and the need to protect your valuable farm assets. Without adequate coverage, one serious accident could potentially threaten your entire operation.
At Copeland Insurance Agency, we can help you determine the appropriate liability limits based on your specific operation, the types of roads your vehicles travel, and the value of your assets that need protection.
Collision and Comprehensive Coverage
While liability coverage protects you against claims from others, collision and comprehensive coverage protect your farm truck itself against various types of damage.
Collision Coverage provides protection when your farm truck is damaged in an accident involving another vehicle or object, regardless of who is at fault. This coverage helps pay for repairs to your truck or provides compensation if it’s deemed a total loss.
Key aspects of collision coverage include repairs or replacement after accidents with other vehicles, coverage for single-vehicle accidents (like rollovers), protection when hitting objects like fences, buildings, or trees, and coverage regardless of fault (though deductibles apply).
Comprehensive Coverage (sometimes called “Other Than Collision” coverage) protects your farm truck from damage caused by incidents other than collisions. This includes theft or vandalism, fire damage, weather-related damage (hail, flood, tornado), falling objects (trees, branches), and animal collisions (like hitting a deer).
A farmer from Wamego, KS, shared this experience: “When a severe hailstorm damaged several of our farm trucks, our comprehensive coverage made all the difference. The insurance covered the repairs, which would have cost us over $12,000 out of pocket.”
According to our research, comprehensive coverage for a semi-truck typically costs around $150–$200 per year, while collision coverage runs about $300–$400 per year. For a pickup truck or grain truck, these costs may be lower.
For valuable farm trucks, we generally recommend including both collision and comprehensive coverage in your policy. The deductible amount you choose will affect your premium—higher deductibles mean lower premiums but more out-of-pocket expense if you file a claim.
Uninsured and Underinsured Motorist Coverage
Uninsured and underinsured motorist coverage provides essential protection for farm truck owners against drivers who either have no insurance or insufficient coverage to pay for damages they cause.
This coverage becomes particularly important when your farm truck is hit by a driver with no insurance, you’re involved in a hit-and-run accident, or the at-fault driver has insurance but their limits are too low to cover all your damages.
According to industry statistics, approximately 13% of drivers nationwide are uninsured, with rates varying significantly by state. This means there’s a real possibility that if your farm truck is damaged by another driver, you could be left covering the costs yourself without this protection.
A client from Topeka, KS, shared this cautionary tale: “My grain truck was sideswiped by an uninsured driver on the highway. The damage was extensive, and without my uninsured motorist coverage, I would have been looking at over $8,000 in repairs that would have come directly out of my farm’s operating budget.”
Uninsured and underinsured motorist coverage typically includes bodily injury protection (covers medical expenses, lost wages, and pain and suffering for you and your passengers) and property damage protection (pays for repairs to your farm truck in states where this coverage is available).
For farm trucks, this coverage is particularly valuable because rural roads where farm trucks often operate may have higher percentages of uninsured drivers, farm trucks represent significant investments that need protection, and injuries sustained in accidents involving larger vehicles can be more severe.
At Copeland Insurance Agency, we typically recommend including uninsured and underinsured motorist coverage in your farm truck insurance policy. For a grain truck worth approximately $50,000, adding this coverage might cost around $100 per year—a small price for significant protection when you consider how often the question “do farm trucks need insurance?” comes up after an accident has already occurred.
How Does Farm Truck Insurance Differ from Standard Auto Insurance?
Farm truck insurance has several key differences from standard auto insurance policies, reflecting the unique ways these vehicles are used in agricultural operations. Understanding these differences can help you secure the most appropriate and cost-effective coverage for your farm vehicles.
When you’re driving to the grocery store in your personal vehicle, the insurance needs are quite different than when you’re hauling a load of hay across your property or transporting livestock to market. This is why farm truck insurance exists as a distinct category.
Farm truck insurance typically accounts for seasonal, limited use patterns rather than the daily commuting assumed in standard auto policies. Your grain truck might log heavy miles during harvest season but sit idle for months afterward—something standard auto insurance doesn’t account for. This seasonal usage often translates into lower premiums compared to regular auto insurance.
The territory of operation is another major difference. While standard auto insurance assumes you might drive anywhere within a large radius, farm truck policies recognize that many agricultural vehicles operate primarily on or near the farm property. This limited territory can mean reduced risk and lower insurance costs.
Farm truck insurance can also be structured differently, often as part of a broader farm policy rather than as a standalone product. This integration allows for potential bundling discounts and more comprehensive protection of your agricultural operation as a whole.
“When we switched from standard commercial auto to specialized farm truck coverage, our premiums dropped by nearly 30%,” shares a fourth-generation farmer from Junction City, KS. “The insurance company finally recognized that my trucks weren’t being driven daily like a delivery service—they were farm tools with a specific purpose and limited use.”
According to our research, the specialized nature of farm truck insurance often results in more affordable coverage compared to standard auto or commercial vehicle policies. At Copeland Insurance Agency, we’ve helped countless farmers save money by ensuring their vehicles are properly classified and covered.
Special Considerations for Farm Truck Insurance
Farm trucks present unique insurance considerations that don’t apply to standard personal vehicles. These special factors reflect the distinctive ways farm trucks are used and the environments they operate in.
Seasonal operation is perhaps the most significant consideration. Unlike your family car that gets regular use year-round, farm trucks often experience intense periods of use during planting and harvest, followed by minimal use at other times. This usage pattern affects how policies are structured and priced, typically resulting in lower premiums compared to vehicles with consistent daily use.
Farm operations also typically involve multiple operators. Your farm truck might be driven by family members, full-time employees, and seasonal workers throughout the year. Your policy needs to account for all these potential drivers, which creates a different risk profile than a personal vehicle typically driven by one or two people.
Cargo considerations also play a major role in farm truck insurance. When you’re hauling valuable livestock, freshly harvested crops, or expensive equipment, you need coverage that protects not just the vehicle but also its contents. This specialized cargo coverage isn’t typically part of standard auto policies.
“Last harvest, one of our grain trucks tipped on a soft shoulder while fully loaded,” recalls a farmer from Abilene, KS. “Having the right insurance saved us not just the cost of the truck repairs but also the value of the grain we lost. That’s something a standard auto policy wouldn’t have covered.”
The on-farm versus public road use split is another unique consideration. Many farm trucks divide their time between private property and public roads, creating coverage needs that standard auto policies aren’t designed to address. At Copeland Insurance Agency, we make sure your policy covers your truck whether it’s moving between fields or making a delivery to the grain elevator in town.
Farm trucks often feature vehicle modifications for agricultural use, such as specialized beds, lifts, or attachments. These modifications need to be properly documented and covered—another area where standard auto insurance falls short.
Can I Use My Farm Truck for Personal Use Under Farm Truck Insurance?
A common question we hear from farmers is whether they can use their farm truck for personal errands while maintaining farm truck insurance coverage. The answer isn’t always straightforward, but in many cases, yes—with some important caveats.
Most farm truck insurance policies do allow for some personal use, but there are typically limitations. Based on our experience working with various insurance carriers, if your truck is used for farming purposes at least 50% of the time, it may still qualify for specialized farm truck insurance even with some personal use mixed in.
The registration of your vehicle plays a significant role in this equation. Trucks with farm license plates (or “farm tags”) typically have more restrictions on personal use. These vehicles are generally limited to farm operations or trips between farms, though some states allow limited personal use such as trips to service centers or supply stores.
“I was worried I’d need separate insurance policies for my truck depending on whether I was hauling feed or taking my kids to their 4-H meeting,” shares a client from Manhattan, KS. “Copeland Insurance helped me understand that my farm policy could cover both, as long as the primary purpose of the vehicle remained agricultural.”
For trucks with standard registration, there are fewer restrictions on personal use, but the vehicle must still qualify as primarily farm-related to receive the specialized coverage and rates. This is where honest communication with your insurance agent becomes crucial.
If you plan to use your farm truck for both agricultural and personal purposes, we recommend being completely transparent about your usage patterns. Misrepresenting how a vehicle is used could potentially lead to claim denials if an accident occurs during unauthorized use.
At Copeland Insurance Agency, we work with farmers across Kansas to find the right balance of coverage for mixed-use farm trucks. We understand that farm life doesn’t always draw clear lines between “work” and “personal” activities—your truck is often an essential tool for both.
Do farm trucks need insurance that covers personal use? In most cases, yes—and finding the right policy that covers all your needs while maximizing available discounts is exactly what we specialize in.
What Affects the Cost of Farm Truck Insurance?
The cost of farm truck insurance isn’t one-size-fits-all. Like the crops and livestock you nurture, premiums are influenced by a variety of factors unique to your operation. Understanding these elements can help you make smarter coverage decisions and potentially trim your insurance costs.
When farmers ask us about what drives their insurance costs, we typically point to several key factors:
The type and value of your vehicle plays a major role in determining premiums. That shiny new $55,000 pickup will naturally cost more to insure than your trusty 25-year-old farm truck. Our research shows that a newer pickup might run you $200-$400 annually for $1 million in liability coverage, while an older semi-truck might cost $950-$1,050 for the same protection.
How you use your truck significantly impacts your rates too. A farm truck that never leaves your property presents less risk than one regularly traveling busy highways. This usage difference can translate to substantial premium savings.
Your driving history tells insurers a lot about risk. Clean driving records typically earn lower premiums, while accidents or violations can push costs higher. This applies not just to you, but to anyone who regularly operates your farm vehicles.
The coverage types and limits you select naturally affect what you’ll pay. More comprehensive protection with higher limits means higher premiums, but also better protection for your farming operation when accidents happen.
Deductible amounts work in inverse proportion to your premium costs. When you agree to pay more out-of-pocket before insurance kicks in (higher deductible), your premium generally decreases. It’s a balancing act between upfront savings and potential future costs.
Even your farm’s location influences your rates. Rural areas with less traffic might see lower premiums than farms near busy highways. Local weather patterns that create recurring risks (like hail or flooding) may also affect what you pay.
Previous claims history is another significant factor. A farm with few or no prior claims generally enjoys lower premiums than one with multiple insurance payouts.
A farmer from Wamego, KS, recently told us: “I was surprised at how much my rates dropped after three claim-free years. It really pays to be careful and implement those safety measures Copeland recommended.”
The number of vehicles you insure can also impact your costs, often positively. Many carriers offer multi-vehicle discounts that make covering your entire farm fleet more affordable.
How Vehicle Usage Impacts Insurance Premiums
The way you use your farm truck has one of the most direct impacts on what you’ll pay for insurance. Insurance companies are essentially risk managers, and how you operate your vehicle fundamentally shapes that risk profile.
Do farm trucks need insurance if they never leave your property? While the legal requirements might differ, the risk factors certainly do. Trucks that stay exclusively on farm property typically qualify for significantly lower rates than those that regularly venture onto public roads. The simple reason? Less exposure to other drivers means fewer potential accidents.
A fourth-generation farmer from Riley County explained it perfectly: “My grandfather’s old pickup never leaves our property—it just shuttles between the barn and fields. We pay about half what we do for our road trucks because it’s never mixing with highway traffic or city driving.”
Seasonal usage patterns create another opportunity for potential savings. Many farm trucks see intense activity during planting and harvest but might sit idle for months at a time. Some insurance carriers offer policies that account for these predictable patterns, allowing you to pay primarily for the coverage you need when you actually need it.
The purpose of your hauling makes a big difference too. Using your truck exclusively for your own farm operations typically costs less than if you’re hauling commercially for others. Commercial hauling often requires different coverage types and higher limits, which can push premiums upward. For-hire trucking operations might see annual costs of $3,000 to $7,500 per truck—substantially more than farm-only operations.
Distance traveled is another key factor. A farm truck that operates within a 50-mile radius presents less risk than one making regular long-distance hauls. More miles mean more exposure to potential accidents, which insurers typically reflect in higher premiums.
Even what you’re hauling matters. Cargo type affects both risk and required coverage. Transporting livestock carries different risks than hauling grain. And if you’re occasionally transporting hazardous materials like certain agricultural chemicals, your insurer needs to know—both for proper coverage and accurate pricing.
At Copeland Insurance Agency, we take time to understand exactly how each farm vehicle is used, ensuring you’re neither underinsured nor paying for coverage you don’t need.
Tips for Saving on Farm Truck Insurance Premiums
While protecting your farm vehicles is essential, there’s no reason to pay more than necessary for quality coverage. Over the years, we’ve helped hundreds of farmers across Kansas find smart ways to trim their insurance costs without sacrificing protection.
One of the most effective strategies is to bundle your policies. Combining your farm truck insurance with other coverages like property insurance or personal auto policies often open ups substantial multi-policy discounts. These savings typically range from 5% to 15%, sometimes more.
“When we consolidated all our farm policies with Copeland Insurance,” shared a wheat farmer from McPherson County, “our overall insurance costs dropped by nearly $2,300 annually. That’s money we put right back into the operation.”
Strategic deductible adjustments can also yield significant savings. By accepting a higher out-of-pocket cost if a claim occurs, you can substantially lower your premium. This approach works particularly well for vehicles you use less frequently or those with lower replacement values. Just make sure you keep your deductible at a level you could comfortably pay if needed.
For those older farm trucks that have been part of your operation for years, consider reviewing collision and comprehensive coverage. When a vehicle’s value has depreciated significantly, you might be paying more for these coverages than makes financial sense. A good rule of thumb: if annual comprehensive and collision premiums exceed 10% of the vehicle’s value, it might be time to reconsider.
Safety improvements not only protect your people and equipment but can also earn you insurance discounts. Many carriers offer premium reductions for vehicles equipped with anti-theft devices, GPS tracking systems, dash cameras, or even fire suppression systems for certain equipment. These investments often pay for themselves through both prevented losses and lower insurance costs.
Maintaining clean driving records for everyone who operates your farm vehicles is perhaps the most fundamental way to keep premiums in check. Many farmers have found that implementing formal safety training for employees who drive farm trucks pays dividends in both fewer accidents and lower insurance costs.
A simple but often overlooked strategy is to pay premiums annually rather than monthly. This approach typically saves 5-10% compared to installment plans with their associated service fees.
Don’t forget to ask about agricultural organization discounts. Membership in farm bureaus or agricultural associations often qualifies you for additional premium reductions that can add up significantly.
Finally, regular policy reviews are essential as your operation evolves. As equipment ages, usage patterns change, or your operation grows, your insurance needs shift too. At Copeland Insurance Agency, we recommend annual coverage reviews to ensure you’re properly protected without paying for unnecessary coverage.
For more detailed information about farm truck insurance costs and saving opportunities, visit our guide on How Much is Farm Truck Insurance?.
Benefits of Insuring Farm Vehicles
When farmers ask “do farm trucks need insurance?” we often discuss more than just legal requirements. There’s a whole range of benefits that come with properly insuring your farm vehicles—benefits that protect not just your equipment, but your entire agricultural operation and peace of mind.
Insurance for farm vehicles isn’t just a checkbox on your compliance list—it’s a crucial safety net for your livelihood. We’ve seen this at Copeland Insurance Agency through the experiences of countless farmers across Kansas and beyond.
One of our clients from Topeka shared a story that really drives this home: “When one of our farm trucks was involved in an accident on a county road, the liability claim exceeded $250,000. Our insurance covered the entire amount—without it, we might have lost the farm my family has owned for generations.”
Financial protection against liability claims is perhaps the most compelling reason to insure your farm vehicles. A single accident can lead to medical bills, property damage costs, and legal expenses that could potentially bankrupt an uninsured operation. With proper coverage, your farm’s assets remain protected even in worst-case scenarios.
Your farm trucks and equipment represent major investments in your operation. With new farm trucks easily costing $50,000 to $100,000 or more, can you afford to replace one out-of-pocket if it’s damaged beyond repair? Insurance ensures you’re not left bearing the full financial burden of unexpected losses.
We’ve also seen how insurance supports business continuity during critical times. A farmer from Manhattan, KS told us how his comprehensive coverage helped him quickly replace a damaged grain truck right before harvest season: “Without that quick turnaround, we would have lost thousands in delayed harvesting. The insurance paid for itself many times over.”
There’s also something to be said for the peace of mind that comes with knowing you’re protected. Farming has enough uncertainties—from weather to market prices—without adding vehicle damage concerns to your plate. Proper insurance coverage lets you focus on what you do best: running your farm.
For many of our clients with financed equipment, insurance isn’t optional—it’s required by their lenders. Maintaining appropriate coverage ensures you stay in compliance with loan requirements and avoid potential complications with your financing.
Kansas farmers are no strangers to severe weather. From hailstorms to tornadoes, protection against weather and natural disasters is especially valuable in agricultural settings where equipment is often exposed to the elements. Comprehensive coverage can make the difference between a minor setback and a major financial blow.
A client from Wamego experienced this firsthand: “After a theft at our property resulted in the loss of two ATVs and damage to a farm truck, our insurance coverage made recovery possible. Without it, we would have struggled to replace that equipment during an already tight financial year.”
At Copeland Insurance Agency, we’ve witnessed countless times how proper farm vehicle insurance has safeguarded our clients’ operations during challenging circumstances. We believe that comprehensive coverage isn’t just an expense—it’s an essential investment in your farm’s resilience and future.
Whether you’re wondering if do farm trucks need insurance from a legal standpoint or considering the practical benefits, the answer is clear: protecting your farm vehicles means protecting your livelihood, your legacy, and your peace of mind.
Frequently Asked Questions About Farm Truck Insurance
Do Farm Trucks Need Insurance If They Never Leave the Farm?
This is a question we hear almost weekly at Copeland Insurance Agency. Technically speaking, if your farm truck never ventures beyond the boundaries of your private property and is used exclusively on your farm, it may not be legally required to carry insurance in most states.
However, before you decide to skip insurance coverage, there are several important factors to consider.
Even on private property, accidents happen. Your truck could be damaged in a collision with other farm equipment, cause property damage to buildings or fences, or be involved in an incident where someone gets injured. Without insurance, you’d be personally responsible for covering all these costs out of pocket.
A farmer from Riley, KS shared a painful lesson with us: “I had an older truck I only used around the farm and figured I’d save money by not insuring it. When a fire broke out in our equipment shed and destroyed it completely, I had to come up with $15,000 to replace it—money that wasn’t in our farm budget. I learned the hard way that insurance isn’t just about legal requirements.”
If your farm truck is financed, the decision may already be made for you. Lenders typically require insurance coverage regardless of where the vehicle is used, as they need to protect their investment until the loan is paid off.
Additionally, on-farm vehicles still face risks like theft, vandalism, and weather damage. A comprehensive policy protects against these perils that have nothing to do with driving on public roads.
And let’s be honest—many “farm-only” trucks occasionally need to travel on public roads, even if it’s just down the road to another field or to a neighbor’s property. Even these infrequent trips require proper insurance coverage to be legal.
At Copeland Insurance Agency, we generally recommend maintaining at least basic insurance coverage even for farm-only vehicles. The peace of mind and financial protection are well worth the relatively modest cost of a farm-specific policy.
Is Farm Truck Insurance Cheaper Than Standard Auto Insurance?
Good news—in many cases, do farm trucks need insurance policies that are more affordable than standard auto insurance. This cost advantage comes from several factors unique to farm vehicles.
Farm trucks typically rack up far fewer miles annually than personal vehicles. While your daily driver might log 12,000-15,000 miles each year, a farm truck used primarily during planting and harvest might only accumulate 2,000-3,000 miles. This limited usage translates to lower risk of accidents and often results in lower premiums.
Insurance companies evaluate farm trucks differently than personal vehicles. Instead of focusing primarily on the driver’s history and vehicle type, they consider factors like your farm’s revenue, operational scope, seasonal use patterns, and the balance between on-farm versus public road usage.
One of our clients from Overland, KS recently told us: “After switching from a standard commercial auto policy to a farm truck policy with Copeland Insurance, we saved nearly 35% on our premium for essentially the same coverage. The key difference was how the vehicle’s use was classified.”
Another significant advantage comes from bundling opportunities. Farm truck insurance can often be combined with broader farm insurance policies, creating substantial multi-policy discounts that aren’t available with standalone auto insurance.
According to our research, if a truck is used for farming purposes at least 50% of the time, farm truck insurance is typically cheaper than standard auto insurance while providing similar or even better protection custom to agricultural needs.
For more detailed information on cost comparisons, we’ve put together a comprehensive guide: Is Farm Truck Insurance Cheaper?
How Can I Customize My Farm Truck Insurance Policy?
No two farms operate exactly the same way, which is why customizing your farm truck insurance policy is so important. The right customization ensures you have appropriate protection for your specific situation without paying for coverage you don’t need.
Working with your agent to determine appropriate liability limits is the first step in customization. At Copeland Insurance Agency, we look at factors like your farm’s total asset value, the typical cargo value your trucks transport, your operating territory, and overall risk exposure. A small hobby farm has very different needs than a large commercial operation spanning multiple counties.
Beyond basic liability, you’ll want to consider which optional coverages make sense for your operation. Comprehensive and collision coverage protects your vehicle itself, while cargo coverage safeguards the value of what you’re hauling. Equipment breakdown coverage can be vital for specialized farm trucks with integrated equipment, and roadside assistance provides peace of mind for breakdowns in remote areas.
A client from Junction City, KS explained how customization worked for their operation: “Copeland Insurance helped us create a custom policy that addressed our unique needs. We have specialized coverage for our grain trucks during harvest season, different coverage for our livestock haulers, and appropriate protection for the pickup trucks we use year-round.”
Deductibles are another area where customization makes sense. You might choose lower deductibles for your newer, higher-value vehicles, while selecting higher deductibles for older trucks to reduce premiums. This strategic approach optimizes your coverage while keeping costs manageable.
Specialized endorsements can further tailor your policy. These might include special equipment coverage for after-market additions to your truck, livestock transport endorsements that protect animals during transit, or seasonal usage adjustments that provide fuller coverage during busy periods and reduced coverage during off-seasons.
Don’t forget to include all potential operators on your policy. This includes family members, employees, and seasonal workers who might drive your farm trucks. Failing to list all operators could result in coverage gaps if an unlisted driver is involved in an accident.
For more information on building a custom farm truck insurance policy that perfectly fits your operation, visit our Farm Truck Insurance page. There, we outline various coverage options and customization opportunities that can be custom to farms of all sizes.
At Copeland Insurance Agency, we take pride in creating personalized insurance solutions for agricultural operations across Kansas. Our agents take the time to walk your property, understand your specific operation, and recommend coverage that provides the protection you need without unnecessary expenses.
Conclusion
After exploring the many aspects of farm truck insurance, the answer to the question “do farm trucks need insurance?” is clear: Yes, in most cases, farm trucks should be insured—not just for legal compliance but for the essential protection they provide to your agricultural operation.
“Your farm vehicles are valuable assets worth protecting. The right insurance policy isn’t just about meeting legal requirements—it’s about safeguarding your livelihood and the future of your farm.” – Copeland Insurance Agency
Farm truck insurance isn’t just another expense—it’s a vital safety net for your agricultural business. I’ve seen how proper coverage has saved farms from financial disaster after accidents or unexpected events. Whether you’re running a small family operation passed down through generations or managing a large commercial enterprise, the right insurance protection ensures that one unfortunate incident doesn’t wipe out years of hard work and investment.
Throughout our discussion, we’ve covered how legal requirements vary from state to state, but the bottom line is that farm trucks traveling on public roads typically need at least basic liability coverage. This isn’t just about avoiding tickets or fines—it’s about protecting your farm’s assets if you’re found responsible for damages or injuries to others.
We’ve also explored how different farm vehicles have unique insurance needs. Your grain hauler faces different risks than your pickup truck, and your tractor requires different coverage than your livestock trailer. Understanding these differences helps ensure you’re properly protected without paying for unnecessary coverage.
The good news is that there are various coverage options available to farmers. From basic liability protection to comprehensive coverage that guards against weather damage, theft, and other non-collision events, you can build a policy that addresses your specific concerns and exposures.
One thing many farmers appreciate learning is that farm truck insurance differs significantly from standard auto insurance in ways that often work in their favor. The seasonal nature of farm work, limited mileage, and specialized use patterns typically translate to lower premiums and more appropriate coverage terms.
Several key factors affect your insurance costs, including the type and age of your vehicles, how and where you use them, your driving history, and the coverage options you select. By understanding these factors, you can make informed decisions about your insurance purchases.
There are also several strategic approaches to reducing your premiums without leaving yourself vulnerable. From bundling policies to adjusting deductibles and implementing safety measures, these strategies can help make comprehensive coverage more affordable for your operation.
Perhaps most importantly, the benefits of proper farm truck insurance extend far beyond merely checking the legal compliance box. The right coverage provides genuine asset protection, ensures business continuity after setbacks, and gives you the peace of mind to focus on what matters most—running your farm.
At Copeland Insurance Agency, we’ve been helping farmers across Kansas protect their valuable assets for years. Our team understands the unique challenges and risks faced by agricultural operations, and we’re committed to providing customized insurance solutions that address your specific needs.
We invite you to contact us to discuss your farm truck insurance needs or to review your current coverage for potential improvements or savings. For more comprehensive information about our farm insurance services, visit our Farm Insurance Services page.
The right insurance coverage isn’t just about protection—it’s about providing the peace of mind you need to focus on what you do best: running your farm.