

Storm damage home insurance: Essential 2026 Guide
Why Understanding Your Storm Damage Home Insurance Coverage Matters
Storm damage home insurance is one of the most critical aspects of protecting your home, yet many homeowners don’t fully understand what’s actually covered until disaster strikes. Here’s what you need to know:
What Storm Damage Home Insurance Typically Covers:
- Wind damage from tornadoes, hurricanes, and severe thunderstorms
- Hail damage to roofs, siding, windows, and other structures
- Lightning strikes and resulting fire or power surge damage
- Water damage from rain entering through storm-damaged openings (like a broken window or damaged roof)
- Falling objects such as trees or branches damaged by wind
What’s Usually NOT Covered:
- Flood damage from rising water, storm surge, or overflowing bodies of water
- Earthquake damage
- Gradual water damage from slow leaks or poor maintenance
- Sewer backup (without additional coverage)
Between 2014 and 2018, homeowners filed more claims for wind and hail damage than any other type of loss—over 1.5 million claims in total. The average cost of these claims was $11,754, and in 2022 alone, insured losses from severe weather events reached $45 billion in the U.S.
Understanding your coverage before a storm hits can mean the difference between a smooth recovery and financial hardship. Many homeowners find too late that they assumed certain damages were covered when they weren’t, or that they had a higher deductible than expected for specific storm types.
At Copeland Insurance Agency, we’ve spent over two decades helping Kansas homeowners steer the complexities of Storm damage home insurance to ensure they have the right protection when severe weather strikes. Let’s break down exactly what your policy covers—and what it doesn’t—so you’re prepared when the next storm rolls through.
Related content about Storm damage home insurance:
What Your Homeowners Policy Covers (and What It Doesn’t)
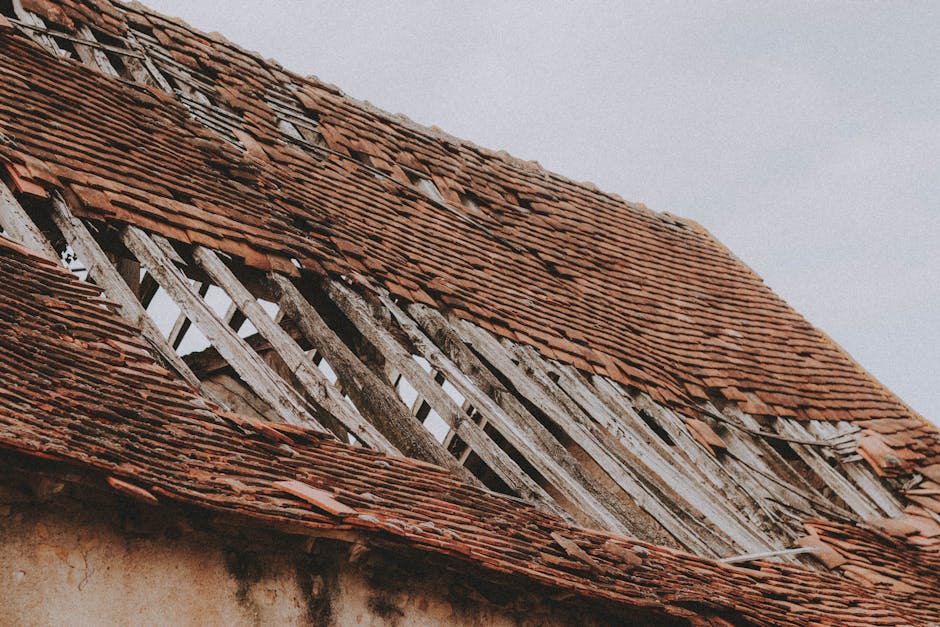
Our standard homeowners insurance policies are designed to protect our homes from a wide array of unexpected events, including many types of storm damage. However, it’s crucial to remember that “standard” can vary between insurers, and specific perils might have unique limitations or exclusions. This is why we always encourage a thorough review of your policy with a trusted agent.
Generally, your homeowners policy will cover damage to your dwelling, other structures on your property (like a detached garage or shed), and your personal belongings. It also typically includes additional living expenses if your home becomes uninhabitable due to a covered loss.
Covered Perils: Wind, Hail, and Lightning
When we talk about storm damage, certain perils are almost universally covered by standard homeowners insurance:
- Wind Damage: This is a big one for us here in Kansas. From the straight-line winds of a severe thunderstorm to the devastating force of a tornado, wind damage is typically covered. This includes damage to your roof, siding, windows, and even if a tree falls on your house due to high winds. In fact, wind and hail damage accounted for more homeowners insurance claims between 2014 and 2018 than any other type of loss.
- Hail Damage: Kansas is no stranger to hailstorms, and hail damage to roofs is one of the most common weather-related insurance claims. Our policies generally cover damage from hail, sleet, ice, and snow. This can include dents to your siding, damage to shingles, or even broken windows.
- Lightning Strikes: If lightning strikes your home, causing a fire, damaging your electrical systems, or leading to a power surge that fries your electronics, our standard policies typically cover these losses.
- Falling Objects: Should a tree or heavy branch, weakened by a storm, fall and damage your home, your policy generally covers the repairs and removal of the debris.
For a deeper dive into how our policies can protect against various risks, explore our comprehensive home coverage options.
The Nuances of Water Damage Coverage
Water damage from storms can be tricky, as coverage often depends on how the water enters your home.
- Covered Water Damage: If your home is physically damaged by a storm—for example, a broken window or a hole in your roof from wind or hail—and rain or snow then enters through that opening, the resulting interior water damage is typically covered. This includes “wind-driven rain” that enters through a storm-created breach. Water damage from a sudden and accidental event, like a burst pipe due to freezing temperatures, is also generally covered.
- Exclusions for Gradual Damage: What’s usually not covered is water damage that occurs gradually due to neglect or lack of maintenance, such as a slow, undetected leak over many months, or mold growth stemming from such issues. Homeowners are expected to take reasonable steps to maintain their property and prevent such problems.
Understanding the difference between wind damage and floodwater damage is crucial for claims, as FEMA provides guidance on this very distinction. We want to ensure you’re clear on what your policy covers in these scenarios. You can learn more about this distinction on FEMA’s website.
Common Exclusions: Floods and Earthquakes
While storm damage home insurance covers many weather-related perils, there are two significant exclusions that often catch homeowners by surprise:
- Flood Damage: This is perhaps the most common misconception. Standard homeowners insurance policies explicitly exclude flood damage. This means damage from rising ground water, overflowing rivers or lakes, heavy rainfall accumulation, or storm surges (if you’re near a coastal area, which isn’t typically an issue for us in Kansas) are not covered. For flood protection, you need a separate policy, typically through the National Flood Insurance Program (NFIP) or a private flood insurance company. We can help you explore personal flood insurance options to ensure you’re protected.
- Earthquake Damage: While less common in Kansas than in some other states, standard homeowners insurance policies also do not cover damage from earthquakes. If you live in an area with seismic activity (even minor), you would need a separate earthquake policy or endorsement. For example, in California, the California Earthquake Authority (CEA) offers such coverage. We offer earthquake coverage options for those who desire this added layer of protection.
It’s also worth noting that damage from sewer or drain backups is typically excluded from standard policies unless you add a specific endorsement for it.
Understanding Key Policy Terms for Storm Damage Home Insurance

Navigating your storm damage home insurance policy can feel like reading a foreign language. However, understanding a few key terms can make all the difference when you need to file a claim. These terms dictate how much financial protection you truly have and how your claims will be paid out. Your policy’s dwelling coverage, for instance, protects the physical structure of your home.
Replacement Cost (RCV) vs. Actual Cash Value (ACV)
This distinction is incredibly important, especially when assessing damage after a storm.
- Replacement Cost Value (RCV): This is what we ideally want for our homes and belongings. RCV coverage pays to replace your damaged property with new items of similar kind and quality without deducting for depreciation. This means if your 15-year-old roof is destroyed by hail, an RCV policy will pay the cost of a brand-new roof, not just what the old one was worth.
- Actual Cash Value (ACV): ACV coverage pays the current market value of the damaged item, deducting for depreciation. If that same 15-year-old roof (with an expected lifespan of 20-25 years) was damaged, an ACV policy might only pay a fraction of the cost of a new roof, leaving you to cover the difference. For instance, if a new roof costs $12,000, but your 15-year-old roof was only valued at $6,000 due to depreciation, an ACV policy would only pay $6,000 (minus your deductible). The same applies to personal property.
Here’s a quick comparison:
| Item | Age | New Cost | ACV Payout (example) | RCV Payout (example) |
|---|---|---|---|---|
| Roof | 10 yrs | $15,000 | $7,500 | $15,000 |
| Television | 5 yrs | $1,000 | $300 | $1,000 |
We recommend opting for RCV coverage whenever possible, particularly for your dwelling and significant personal property items. It offers far greater financial protection and peace of mind. To help you plan, we have tools to help you estimate the replacement cost of your home.
Your Deductible: Standard vs. Special Storm Deductibles
Your deductible is the amount you, the policyholder, are responsible for paying out-of-pocket before your insurance company begins to pay for a covered loss.
- How Deductibles Work: If your deductible is $1,000 and your covered storm damage repairs cost $5,000, your insurance company will pay $4,000, and you pay the first $1,000.
- Special Storm Deductibles: This is where it gets interesting, especially in areas prone to specific types of severe weather. While Kansas doesn’t typically see hurricane deductibles, it’s common for policies here to have separate, higher deductibles for windstorm or hail damage. These might be a flat dollar amount (e.g., $2,500) or a percentage of your home’s insured value (e.g., 1% or 2% of the dwelling coverage). For a home insured for $300,000, a 1% wind/hail deductible would be $3,000—significantly higher than a standard $1,000 deductible. We advise you to check your policy specifically for these types of deductibles.
Additional Living Expenses (ALE) for When You’re Displaced
If a covered storm event makes your home uninhabitable, your homeowners policy typically includes Additional Living Expenses (ALE) coverage, sometimes called “Loss of Use.”
-
What it Covers: ALE helps cover the necessary increase in living expenses incurred while your home is being repaired or rebuilt. This can include:
- Hotel or rental home costs
- Restaurant meals (above your typical food budget)
- Temporary pet boarding
- Extra transportation costs (e.g., if you have to drive further to work or school)
- Storage fees for your belongings
-
When it Applies: ALE kicks in when your home is rendered unsafe or unusable due to a covered peril. It does not typically apply if you’re just without power or water for a few days unless there’s physical damage to your home.
It’s crucial to keep all receipts for these expenses, as your insurer will require them for reimbursement. If your home has been damaged, we encourage you to review resources like those from the Texas Department of Insurance for general guidance on what to do if your home is damaged.
The Storm Damage Claim Process: A Step-by-Step Guide

When a storm hits and damages your home, the moments immediately following can feel overwhelming. But taking a structured approach to the claims process can make a significant difference in your recovery. Here’s our step-by-step guide to navigating your storm damage home insurance claim.
Step 1: Immediate Actions to Take After a Storm
Your safety and preventing further damage are our top priorities.
- Ensure Safety First: Check on your family and pets. If your home is severely damaged, evacuate to a safe location. Do not enter areas with structural damage or downed power lines.
- Prevent Further Damage: Your policy requires you to take reasonable steps to protect your property from additional loss. This might include:
- Tarping your roof: If you have a hole in your roof, cover it with a tarp or plastic sheeting to prevent rain from entering and causing more damage. The OSHA safety guide for tarping roofs offers valuable safety tips.
- Boarding up broken windows or doors.
- Drying out wet areas: Use fans or dehumidifiers to prevent mold growth, which can start within 24-48 hours.
- Trimming dangerous tree branches: If a branch is hanging precariously, trim it or hire a professional.
- Document Temporary Repairs: Keep all receipts for materials and labor for any temporary repairs you make. These costs are usually reimbursable as part of your claim. However, avoid making extensive permanent repairs until after your insurance adjuster has had a chance to assess the damage.
- Contact Your Provider: As soon as it’s safe, reach out to us at Copeland Insurance Agency or directly to your insurance carrier to report the damage. You can easily report a claim with your provider through our service center.
Step 2: Documenting Damage for Your Storm Damage Home Insurance Claim
Thorough documentation is your best friend when filing a claim. It provides concrete evidence of the damage and helps ensure you receive a fair settlement.
- Photographs and Videos: Take extensive photos and videos of all damage, both inside and outside your home. Capture multiple angles, close-ups, and wider shots showing the context. If you have “before” photos of your home, they can be incredibly helpful.
- Detailed List of Damaged Items: Create a comprehensive list of all damaged or destroyed personal property. Include brand names, model numbers, where you purchased them, and their approximate value. If you have receipts, even better. A home inventory created before the storm is invaluable here.
- Contractor Estimates: Before you even file a claim, it can be beneficial to get an estimate from a reputable local contractor for the repair work. This gives you an independent assessment of the damage and potential costs. We can help guide you on how to approach this.
- Keep Records: Maintain a log of all communications with your insurance company, including dates, times, names of people you spoke with, and a summary of the conversation. Keep copies of all emails, letters, and documents.
For more detailed advice on what to document, Consumer Reports offers excellent guidance on how to file a claim after a storm.
Step 3: Filing Your Claim and Working with an Adjuster
Once you’ve taken immediate steps and documented the damage, it’s time to formally file your claim.
- Contact Your Insurer Promptly: Your policy generally requires you to notify your insurer “in a timely manner.” Delaying can complicate your claim and potentially impact coverage.
- Get a Claim Number: When you report the damage, you’ll be assigned a claim number. Keep this handy for all future correspondence.
- The Adjuster’s Role: An insurance adjuster will be assigned to your claim. Their job is to inspect the damage, determine what’s covered under your policy, and estimate the cost of repairs. They may conduct an in-person visit or, increasingly, perform remote assessments using photos or video calls. If you’re uncomfortable with a virtual assessment or the damage is extensive, you can request an in-person visit.
- Be Prepared for the Adjuster: Have all your documentation ready – photos, videos, lists of damaged items, and contractor estimates. Be ready to walk them through all areas of damage.
- Beware of Scammers: After a major storm, unfortunately, scammers can emerge. Be cautious of anyone asking for confidential information like your Social Security number or bank account details. Adjusters should present identification. FEMA provides an infographic on who’s knocking at your door to help you identify legitimate adjusters.
Step 4: Handling Disagreements and When to Hire a Public Adjuster
Ideally, your claim process will be smooth, but sometimes disagreements arise regarding the extent of damage or the settlement offer.
- Review the Settlement Offer Carefully: Don’t feel pressured to accept the first offer. Compare it to your contractor’s estimates and your own assessment of the damage.
- Disputing a Low Offer: If you believe the offer is too low, don’t cash any checks that might be considered a “final settlement.” Instead:
- Talk to the Claims Manager: Explain your concerns, provide additional documentation (like detailed contractor bids), and reference your policy language.
- Contact the Claims Executive: If you’re still not satisfied, you can escalate your concerns to higher-ups within the insurance company.
- State Department of Insurance: If you feel you’re being unfairly treated, you can file a complaint with the Kansas Department of Insurance. They regulate insurers and can mediate disputes.
- When to Hire a Public Adjuster: For very large, complex claims, or if you’re consistently disagreeing with your insurer, you might consider hiring a public adjuster. Unlike the adjuster assigned by your insurance company (who works for the insurer), a public adjuster works exclusively for you, the policyholder. They will assess the damage, prepare your claim, and negotiate with your insurer on your behalf.
- Fees: Public adjusters typically charge a percentage of the final settlement (often 10-12%, though it can vary).
- Licensing: Ensure any public adjuster you consider is licensed in Kansas. You can check the NAPIA website to find a public adjuster and verify their credentials.
Understanding your options and rights is key. If you ever have questions about whether your claim is covered, we’re here to help.
Proactive Measures to Minimize Storm Damage
While storm damage home insurance is essential for recovery, taking proactive steps to protect your home can reduce the likelihood and severity of damage in the first place. Prevention is always better (and often cheaper) than repair!
- Regular Roof Inspection and Maintenance: Your roof is your home’s first line of defense against storms.
- Inspect your roof annually (or more often after severe weather) for loose, cracked, or missing shingles.
- Trim tree branches overhanging your roof to prevent them from falling during high winds.
- Keep gutters and downspouts clear to ensure proper drainage, preventing water buildup and ice dams.
- If you’ve recently installed a new roof, let us know! It can sometimes impact your premium positively, and we can advise on whether you should tell your agent if you get a new roof.
- Secure Outdoor Items: Before a storm hits, bring in or secure anything that could become a projectile in high winds—patio furniture, grills, trash cans, decorations, and toys.
- Protect Windows and Doors: Consider installing storm shutters or impact-resistant glass if you live in an area prone to severe hailstorms or high winds.
- Install Surge Protectors: Protect your valuable electronics from lightning-induced power surges by using surge protectors.
- Review Your Landscaping: Opt for storm-resistant trees and shrubs, and ensure they are well-maintained.
- Understand Your Home’s Structure: Did you know certain roof types, like a hip roof, can offer better wind resistance than a gable roof? This can sometimes even influence your insurance rates. Learn more about hip vs. gable roof insurance benefits.
By investing a little time in prevention, you can significantly reduce your risk and potentially save yourself the hassle of filing a claim.
Frequently Asked Questions about Storm Damage and Insurance
We often hear similar questions from our clients in Manhattan, Salina, Topeka, and across Kansas after a storm. Here are some of the most common ones:
How long do I have to file a claim?
Most insurance companies require you to file a claim “in a timely manner.” While many policies allow up to one year from the date of loss, it’s always best to file as soon as possible. There’s also a statute of limitations for property damage claims, which is commonly two years in most states, including Kansas. However, delays can make it harder to prove the damage was storm-related and not from other causes. For more general guidance, you can refer to FAQs like those from the Texas Department of Insurance.
Will filing a storm damage claim increase my premium?
This is a common concern. Unfortunately, filing a claim, even if it’s denied or if the payout is below your deductible, can sometimes affect your insurance rates or even lead to non-renewal of your policy. Insurers track claims through databases like the Comprehensive Loss Underwriting Exchange (CLUE) report. While an isolated claim might not drastically impact your premium, multiple claims over a short period almost certainly will. It’s a delicate balance between protecting your assets and managing your insurance profile. We can help you weigh the pros and cons based on your specific situation. You can also explore why insurance premiums are rising in general.
What if my neighbor’s tree damaged my house?
If your neighbor’s tree falls on your house due to a storm (an “act of nature”), your homeowners insurance policy will typically cover the damage to your home and the cost of removing the tree from your property. Your neighbor’s policy usually won’t pay unless you can prove they were negligent—for example, if the tree was clearly dead or diseased, and they failed to remove it despite knowing the risk. Documenting the tree’s condition before a storm can be helpful in such cases.
Conclusion
Navigating storm damage home insurance can seem daunting, but with the right knowledge and a trusted partner, you can feel confident in your protection. We’ve seen the devastation storms can bring to homes and families across Kansas, from Junction City to Manhattan, and we understand the importance of clear, comprehensive coverage.
The key takeaways are:
- Understand Your Policy: Know what’s covered (wind, hail, lightning, certain water damage) and what’s excluded (floods, earthquakes, gradual damage). Pay close attention to your deductibles, especially special storm deductibles.
- Document Everything: From pre-storm photos to post-storm damage, meticulous records are your strongest asset in a claim.
- Act Promptly and Proactively: Take immediate steps to prevent further damage, and file your claim as soon as it’s safe. Proactive home maintenance can significantly reduce your risk.
- Don’t Settle for Less: If you disagree with an offer, know your rights and don’t hesitate to seek further assistance.
At Copeland Insurance Agency, we pride ourselves on providing quality insurance products and caring service at affordable prices. Our dedicated team is here to help you protect your most valuable asset—your home. We’re licensed in nine states, including Arizona and Texas, but our roots are firmly planted in Kansas, serving communities like Salina, Topeka, and Abilene with unwavering dedication.
Don’t wait until the next storm is on the horizon. We encourage you to talk to an agent about your homeowners insurance needs today. Let us help you ensure your home is fully protected, giving you peace of mind no matter what Mother Nature throws our way.